
When does refinery decarbonization investment pay off for aging assets




For operators of aging refining assets, the core question is no longer whether to decarbonize, but when refinery decarbonization investment begins to deliver measurable returns. As carbon costs, compliance pressure, and fuel-market volatility intensify, decision-makers need a clear framework to evaluate payback, risk exposure, and long-term asset competitiveness in a hydrogen- and CCUS-driven energy transition.
What decision-makers are actually asking when they evaluate refinery decarbonization investment
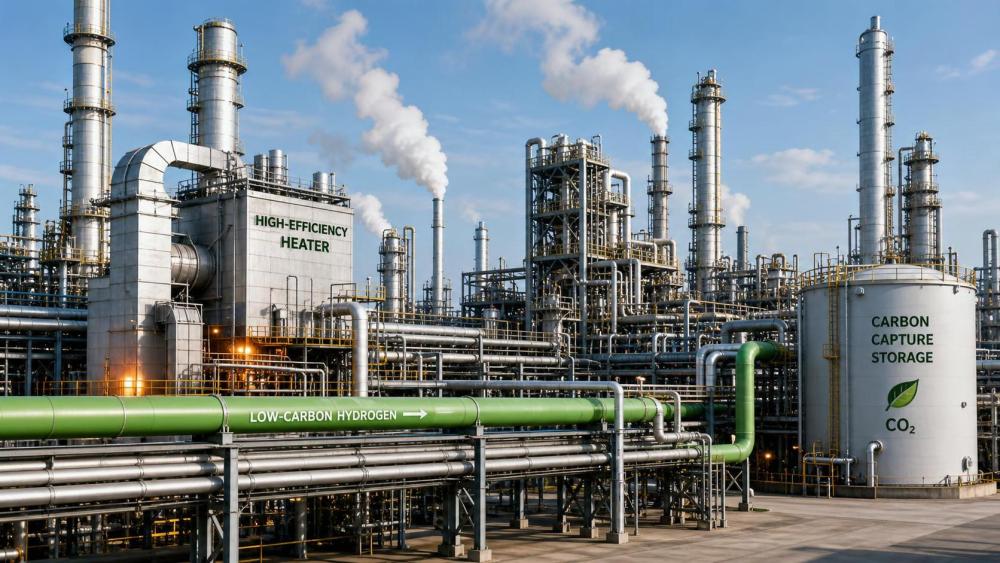
The core search intent behind refinery decarbonization investment is commercial, not theoretical. Executives want to know when capital deployed into aging assets starts producing defendable financial and strategic returns.
They are not looking for generic net-zero language. They need an investment logic that connects emissions reduction measures to margin protection, compliance cost avoidance, operational resilience, and future asset relevance.
For most enterprise decision-makers, the real question is this: does decarbonizing an older refinery extend competitive life at an acceptable payback period, or does it accelerate capital exposure in a declining configuration?
The answer depends less on headline technology and more on asset age, process complexity, hydrogen demand profile, fuel mix, local carbon policy, and the refinery’s role in an evolving regional market.
When does decarbonization investment usually start paying off for aging refinery assets?
In practical terms, refinery decarbonization investment starts paying off when it reduces cash operating exposure faster than it increases capital burden. That threshold can arrive earlier than many operators expect.
In regions with rising carbon prices, strict fuel standards, and aging fired equipment, returns often begin through avoided costs rather than through direct new revenue. That distinction matters for investment timing.
Many projects show value in three overlapping windows. The first is short-term compliance and energy efficiency. The second is medium-term margin stabilization. The third is long-term strategic repositioning.
Short-term payback often comes from heat integration, flare reduction, steam-system optimization, electrification of selected utilities, and digital energy management. These measures can improve energy intensity without changing core refining configuration.
Medium-term returns emerge when the refinery lowers exposure to purchased fossil hydrogen, carbon-intensive process heat, or emissions-heavy power. This is where low-carbon hydrogen and CCUS begin to matter economically.
Long-term payback depends on whether the site can remain relevant in a lower-carbon fuels system. If not, even technically successful projects may struggle to justify their capital over the full asset life.
Which factors have the biggest impact on payback?
The strongest drivers of payback are carbon cost trajectory, refinery energy intensity, hydrogen consumption, remaining mechanical life, maintenance backlog, and access to low-carbon infrastructure near the site.
A refinery with high hydrogen demand for hydroprocessing can justify decarbonization faster if it can source or produce lower-carbon hydrogen at scale. This becomes especially important under tighter product specifications.
Sites facing frequent turnarounds, aging heaters, or inefficient steam networks often have faster payback from targeted upgrades because they are already carrying hidden operating penalties that decarbonization can reduce.
Another major variable is regional policy design. Carbon taxes, emissions trading systems, tax credits, clean fuel standards, and industrial grants can compress payback by several years when combined effectively.
Electricity price structure also matters. Electrification only helps if power is competitively priced and low carbon. Otherwise, operators may shift emissions accounting without creating a real economic advantage.
Finally, the refinery’s strategic role is decisive. A coastal export hub, integrated petrochemical site, or hydrogen corridor anchor may support larger investments than an isolated inland plant serving shrinking local demand.
How should leaders separate attractive projects from capital traps?
The first discipline is to avoid treating all decarbonization measures as one investment category. Aging assets require a portfolio view, because each lever has a different risk profile and payoff horizon.
Low-capex efficiency projects usually deserve priority because they improve economics under almost any market scenario. These are often the foundation moves that create room for larger hydrogen or CCUS decisions later.
The second discipline is to test every project against the remaining economic life of the asset. A technically elegant retrofit does not create value if the refinery may be structurally disadvantaged within a decade.
Third, leaders should distinguish between investments that defend current earnings and investments that depend on uncertain future premiums. Defensive projects are usually easier to underwrite for aging sites.
Capital traps tend to share common features: long payback periods, dependence on unconfirmed policy support, major outage risk, weak integration with existing systems, and no credible role in a regional low-carbon network.
Attractive projects, by contrast, reduce present operating costs, improve compliance certainty, fit existing turnaround schedules, and leave open future pathways for hydrogen, carbon capture, or partial site repurposing.
Why low-carbon hydrogen and CCUS often change the investment case
For many refineries, the largest decarbonization challenge is not electricity but process emissions and hydrogen use. That is why low-carbon hydrogen and CCUS often have disproportionate strategic importance.
Hydrogen is already embedded in refining economics through hydrotreating and hydrocracking. Replacing carbon-intensive hydrogen production with lower-carbon supply can directly reduce scope 1 emissions in a material way.
If the site has access to large-scale electrolysis, pipeline hydrogen, or blue hydrogen with credible capture rates, the business case can strengthen further when carbon exposure is high and fuel quality rules tighten.
CCUS becomes relevant where refinery emissions are concentrated enough to capture efficiently and where storage or utilization infrastructure is bankable. Without transport and storage certainty, economics deteriorate quickly.
Decision-makers should not evaluate these options in isolation. The strongest cases usually come from integrated design: lower-carbon hydrogen, optimized utilities, selective electrification, and targeted carbon capture working together.
This systems approach matters because refinery decarbonization investment rarely pays off through a single intervention. Value is created by reducing multiple cost and risk exposures across the operating model.
What does a practical payback framework look like for an aging refinery?
A useful framework starts with asset triage. Leadership should classify the refinery as defend, optimize, transform, or harvest. Without that classification, payback discussions become disconnected from corporate strategy.
A defend asset has durable market relevance and warrants selective growth-oriented decarbonization. An optimize asset needs disciplined efficiency and compliance upgrades. A transform asset may pivot toward hydrogen or low-carbon fuels.
A harvest asset should generally avoid large discretionary capital unless required for safety, compliance, or near-term cash preservation. This is where many boards make costly errors through strategic ambiguity.
Next, model value across four lines: avoided carbon cost, reduced fuel and utility spend, lower maintenance or reliability loss, and preserved market access for compliant products or strategic customers.
Then stress-test assumptions. Use downside cases for carbon prices, power prices, hydrogen costs, subsidy durability, and throughput. Aging assets rarely fail because of the base case. They fail under stressed conditions.
Finally, align project timing with turnarounds and infrastructure milestones. A good project with bad timing can destroy returns. Integration discipline often matters as much as technology choice.
What risks should boards and investment committees pay closest attention to?
The first risk is overestimating the remaining commercial life of the refinery. If market demand, regulation, or product slate changes faster than expected, even sensible projects can lose economic support.
The second risk is underestimating execution complexity. Retrofit work in aging facilities can trigger integrity issues, unplanned downtime, and cost escalation, especially where documentation or equipment condition is weak.
Third is technology-path dependency. Committing too early to one hydrogen or carbon capture pathway may limit future flexibility if regional infrastructure, standards, or offtake markets evolve differently.
There is also policy concentration risk. Some projects appear attractive only because of a single credit regime or subsidy structure. Boards should ask whether the investment still works under partial policy deterioration.
Reputation and stakeholder risk should not be ignored either. Investors and governments increasingly distinguish between credible operational decarbonization and symbolic capital deployment with limited emissions impact.
The most resilient decisions are those that improve present economics, satisfy foreseeable regulation, and preserve strategic optionality even if the transition unfolds unevenly across regions and product markets.
Where aging refineries are most likely to create real value from decarbonization
The strongest value cases typically appear in refineries with high energy intensity, meaningful hydrogen consumption, and a realistic operating horizon long enough to capture medium-term returns from targeted upgrades.
Integrated sites with petrochemicals, export orientation, or proximity to industrial clusters often gain more because they can share hydrogen, carbon transport, storage, and utility infrastructure across multiple assets.
Refineries located in jurisdictions with rising carbon costs and strong low-carbon policy signals also move up the value curve faster. In those settings, delay can be more expensive than early action.
By contrast, small standalone assets with poor logistics, limited remaining life, or structurally weak margins should be evaluated very carefully. Decarbonization does not automatically rescue a declining business model.
For those sites, the better strategic outcome may be selective emissions reduction combined with phased repurposing toward storage, hydrogen logistics, terminal services, or other lower-carbon infrastructure roles.
Conclusion: the payoff starts when decarbonization strengthens competitiveness, not just compliance
For aging assets, refinery decarbonization investment pays off when it does more than lower emissions on paper. It must reduce operating exposure, protect margins, preserve market access, and support a credible future role.
That usually means starting with efficiency and reliability measures, then moving toward low-carbon hydrogen, electrification, and CCUS where site conditions and regional infrastructure justify deeper capital commitment.
Enterprise leaders should resist broad narratives and focus on asset-specific economics. The right answer is rarely whether to invest in decarbonization at all, but which sequence of investments creates durable value.
In a hydrogen- and carbon-constrained industrial system, aging refineries can still compete. But their investments pay off only when decarbonization is tied directly to cash resilience, strategic relevance, and disciplined timing.
Related News
- How CO2 compression capacity shapes CCUS systems for cement plantsAug 30, 2026CCUS systems for cement plants depend on the right CO2 compression capacity. Explore design, energy, reliability, and transport factors for resilient projects.
- When does refinery decarbonization investment pay off for aging assetsAug 17, 2026Refinery decarbonization investment pays off when aging assets cut carbon, energy, and compliance costs while protecting margins. See the key payback drivers and strategic timing.
- What Delays CCUS Infrastructure Projects Most: Permitting, CO2 Transport, or Storage Readiness?Aug 11, 2026CCUS infrastructure projects often stall on storage readiness before permitting or CO2 transport. Learn which bottleneck delays projects most and how to reduce schedule risk faster.
- How to Compare CCUS Systems Manufacturers for Industrial CO2 ProjectsJul 12, 2026CCUS systems manufacturers vary widely in process fit, reliability, and lifecycle risk. Learn how to compare suppliers for industrial CO2 projects and choose a bankable, integration-ready solution.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Elena Carbon
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.