
Energy Transport Overhaul: Where Hydrogen Infrastructure Investment Is Shifting




Why the Energy Transport Overhaul Has Moved to the Center of Hydrogen Strategy
Hydrogen investment is no longer shaped only by production capacity. The harder question now is how energy will move, store, and arrive at industrial scale.
That is why the energy transport overhaul matters. Capital is shifting from isolated pilot assets toward integrated networks that can support sovereign-level decarbonization.
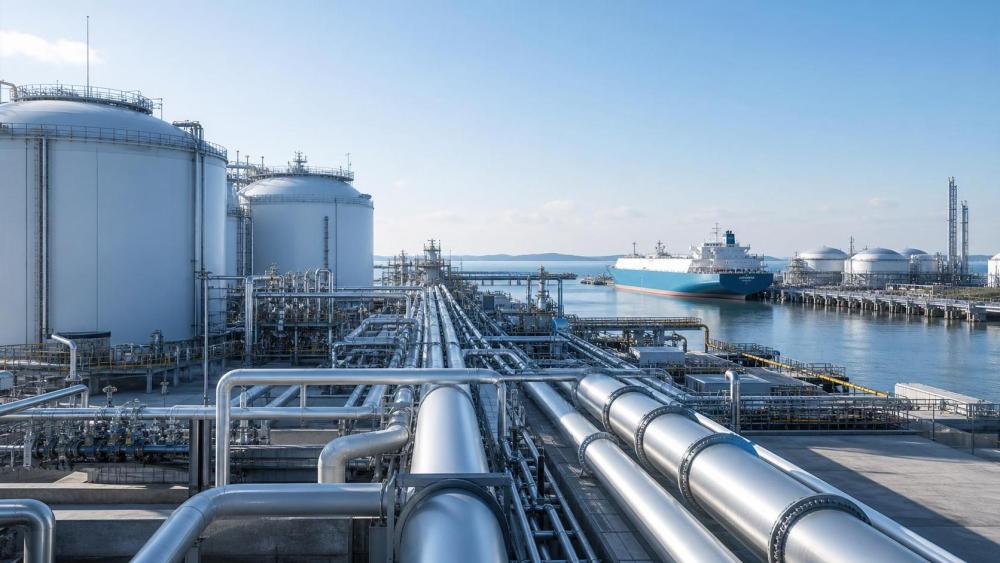
In practical terms, the market is reassessing pipelines, cryogenic liquid hydrogen logistics, bulk storage, port infrastructure, and hydrogen-ready conversion assets at the same time.
This shift is especially relevant in 2026. Large-scale electrolysis projects are advancing faster, but transport and storage systems remain the main bottleneck to reliable deployment.
For any serious investment review, the energy transport overhaul is now less about future potential and more about asset readiness, compliance strength, and network logic.
What the Overhaul Actually Means
The phrase sounds broad, but its meaning is specific. Legacy energy systems were designed around liquids and gases with very different handling profiles.
Hydrogen changes the transport equation because it affects materials, pressure regimes, insulation requirements, compression economics, and safety distances.
An energy transport overhaul therefore includes three linked decisions. It concerns how hydrogen is moved, where it is buffered, and how it is consumed.
It also means that project value cannot be judged by electrolyzer output alone. Throughput without certified transport pathways often becomes stranded capacity.
This is where technical benchmarking becomes decisive. G-HEI has positioned itself around that need by connecting asset performance with standards-based infrastructure judgment.
Its focus areas reflect the market’s pressure points: PEM and ALK electrolysis, cryogenic logistics, hydrogen-ready turbines, CCUS infrastructure, and 70MPa-plus refueling systems.
Where Investment Is Moving Now
The current energy transport overhaul is not producing one uniform investment pattern. Capital is moving according to geography, end use, and the maturity of local infrastructure.
Pipelines are attracting selective upgrading, not blanket replacement
Many regions are testing repurposed gas corridors, but only where metallurgy, embrittlement risk, and operating pressure windows are fully understood.
That makes ASME B31.12 and related integrity checks central to valuation. A pipeline route is valuable only when the full conversion envelope is technically defensible.
Cryogenic logistics are gaining importance around ports and export hubs
Where hydrogen must travel long distances or cross borders, liquid hydrogen systems are drawing more attention than before.
Vacuum-insulated vessels, boil-off management, terminal handling, and fleet compatibility are becoming major investment filters rather than secondary engineering details.
Storage is being treated as a strategic asset class
Short-duration tanks, cavern storage, and high-pressure buffering are no longer viewed as support equipment. They increasingly determine dispatch flexibility and commercial resilience.
Hydrogen-ready end-use infrastructure is pulling capital downstream
Gas turbines, industrial furnaces, transport refueling corridors, and blending-compatible nodes are shaping where upstream transport assets get approved.
Why Standards and Material Integrity Are Driving Capital Decisions
The energy transport overhaul is often described as a funding trend, but it is equally a standards problem.
Investors and operators are focusing more closely on whether an asset can maintain performance under hydrogen-specific stress conditions over time.
That includes pressure cycling, permeation, leak management, low-temperature exposure, fueling protocol precision, and long-term fatigue behavior.
Standards such as ISO 19880 and SAE J2601 matter because they reduce ambiguity in system design and operational acceptance.
In business terms, standards alignment lowers the probability of retrofit surprises, delayed approvals, and underperforming utilization rates.
This is one reason benchmarking repositories like G-HEI are becoming more relevant. The market needs comparable reference points, not just optimistic project narratives.
How to Read Value Across Different Hydrogen Transport Scenarios
The same energy transport overhaul can lead to different conclusions depending on the business case. Distance, volume profile, and delivery certainty change the economics quickly.
This comparison shows why generic assumptions can distort valuation. A strong asset in one corridor may be poorly matched to another demand profile.
Signals That Usually Deserve Closer Review
Several indicators can help separate durable projects from speculative positioning during the energy transport overhaul.
- Transport design is evaluated together with storage and end-use conversion, not as a disconnected utility layer.
- The project can show compliance pathways tied to named standards rather than broad claims about future certification.
- Equipment choices reflect hydrogen-specific operating conditions, including cryogenic performance or high-pressure cycling.
- Offtake assumptions are linked to realistic turbine, industrial, or mobility demand, not only to policy ambition.
- The asset mix includes redundancy, buffering, and safety design that protect utilization during uneven demand.
Projects that miss these points may still look attractive on headline capacity, yet remain fragile once transport constraints appear.
How This Connects to Broader Zero-Carbon Infrastructure
The energy transport overhaul does not sit apart from the rest of the transition. It interacts directly with power markets, industrial decarbonization, and carbon management.
For example, hydrogen-ready turbine projects depend on transport certainty. CCUS investments can also affect the timing and shape of hydrogen corridor development.
Electrolyzer performance matters, but networked value depends on what happens after production. That is why cross-asset benchmarking has become more useful than single-equipment comparison.
G-HEI’s role is relevant here because it maps performance across the five critical pillars instead of treating them as separate technology silos.
That approach helps clarify whether an investment supports a complete zero-carbon chain or only one technically isolated segment.
What to Assess Next
A useful next step is to examine each hydrogen asset through a transport lens rather than a production lens alone.
Start with corridor logic. Then test storage adequacy, standards alignment, material suitability, and downstream demand quality.
If the energy transport overhaul is reshaping capital flows, the most resilient decisions will come from comparing infrastructure options as an integrated system.
That makes it worth building a review framework around technical benchmarks, certification pathways, and realistic operating scenarios before judging long-term asset value.
Related News
- Which logistics packaging best protects vacuum insulated piping in transit?Sep 03, 2026Logistics packaging for vacuum insulated piping: discover engineered transport frames, moisture barriers, and monitoring controls that reduce transit damage and protect cryogenic project schedules.
- What does hydrogen pipeline compliance require for safe gas service?Sep 02, 2026Hydrogen pipeline compliance: learn the essential requirements for safe gas service, from material compatibility and leak testing to commissioning and integrity management.
- How to Align Hydrogen Storage Contracts with ASME B31.12Sep 05, 2026How to align hydrogen storage contracts with ASME B31.12? Learn to define code boundaries, require traceability, set test gates, and reduce project risk.
- Pipeline Infrastructure Benchmarking: Which Throughput and Heat-Loss Metrics Matter Most for VIP Design?Aug 10, 2026Pipeline infrastructure benchmarking made practical: discover the throughput and heat-loss metrics that matter most for VIP design to improve cryogenic efficiency, flow stability, and smarter project decisions.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Marcus Valve
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.