
Energy Industry News: What New Policy Shifts Mean for Hydrogen Projects




Why energy industry news now signals a harder turn for hydrogen projects
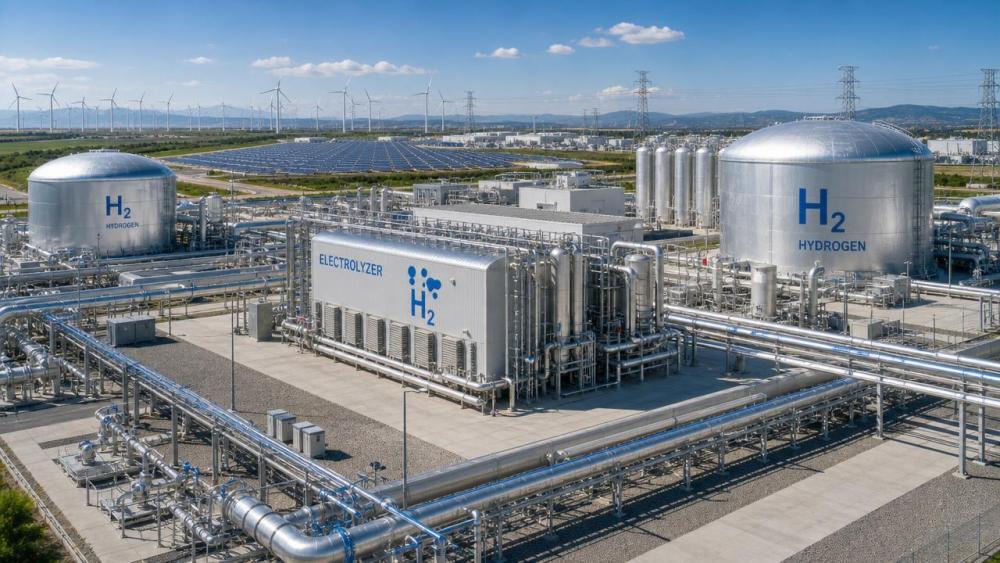
Energy industry news is no longer centered on ambition alone. It is increasingly shaped by policy language, permitting detail, grid access rules, and cross-border compliance requirements.
That shift matters because hydrogen projects have entered a more demanding phase. Capital is still available, but it is moving toward assets that can prove resilience, traceability, and operational discipline.
In practical terms, new policy shifts are redefining how electrolysis plants are sized, how hydrogen is transported, and how infrastructure risk is priced.
The stronger signal in recent energy industry news is that governments now want measurable performance, not just declared decarbonization intent.
For hydrogen developers, utilities, and infrastructure investors, this creates a more selective market. It also creates a clearer one.
Projects aligned with safety standards, material integrity, and sovereign energy security are moving closer to strategic relevance. Projects built on subsidy assumptions alone look weaker than they did two years ago.
This is where a technical benchmarking perspective becomes useful. Platforms such as G-HEI reflect a wider industry reality: hydrogen is now judged across the full zero-carbon chain, not as a single production technology.
The policy shift is broader than subsidies and much closer to infrastructure design
Recent energy industry news often highlights incentives, tax credits, or public funding windows. Those are important, but they are not the whole story.
The deeper change is that policy now reaches directly into engineering choices. It affects source power qualification, emissions accounting, storage protocols, blending rules, and transport safety validation.
More jurisdictions are tightening definitions around low-carbon hydrogen. That affects project bankability because eligibility rules now depend on verifiable operating conditions.
This also changes timing. A project can be technically ready yet commercially delayed if its electricity matching logic, certification pathway, or pipeline material plan is not aligned.
From recent market behavior, four policy themes stand out:
- Stricter carbon intensity accounting for hydrogen production and transport.
- Higher scrutiny on storage, refueling, and pressure-system safety.
- More formal links between hydrogen plans and domestic industrial strategy.
- Greater integration between hydrogen policy and CCUS, power, and grid planning.
Taken together, they show why energy industry news now reads less like a funding cycle and more like a systems transition.
Why these changes are becoming more visible in 2026
The timing is not accidental. Hydrogen has moved beyond pilot symbolism and into the stage where infrastructure mistakes become expensive and politically visible.
Governments are responding to three pressures at once: energy security, industrial competitiveness, and decarbonization credibility. Hydrogen sits at the intersection of all three.
That means policy is becoming more exacting. It must satisfy climate goals without increasing import dependence, grid instability, or public safety concerns.
Another reason is scale. Megawatt-scale electrolysis, cryogenic logistics, hydrogen-ready gas turbines, and 70MPa refueling systems require standardized discipline that smaller pilots could postpone.
G-HEI’s five-pillar view mirrors this market evolution. Electrolysis, liquid hydrogen logistics, hydrogen-ready power, CCUS infrastructure, and refueling are now tightly connected in policy design.
The result is visible across energy industry news: project value increasingly depends on how well one asset fits a larger sovereign-scale system.
The new filters shaping investment quality
Impact is spreading across the full hydrogen value chain
The most important takeaway from current energy industry news is that disruption does not stop at project origination. It reaches every operating layer.
Electrolysis projects face new pressure around operating profiles, water access, and stack durability economics. Lower-cost electricity alone is no longer enough to support the investment case.
In logistics, cryogenic transport and storage are receiving more attention because long-distance hydrogen movement is becoming a strategic rather than experimental concern.
For gas turbine applications, hydrogen-readiness claims are also being tested more carefully. Policymakers want proof around combustion behavior, retrofit feasibility, and emissions outcomes under real conditions.
CCUS is part of the same discussion. In some regions, policy treats carbon capture as a bridge enabler for large industrial decarbonization where green hydrogen supply is not yet sufficient.
Refueling infrastructure is seeing another kind of change. Safety validation, dispensing reliability, and protocol compliance now weigh heavily on project approval and insurance treatment.
This explains why standards such as ISO 19880, ASME B31.12, and SAE J2601 are appearing more often in energy industry news and project reviews. Standards are moving from back-office reference to front-end strategy.
What deserves closer attention before the next investment cycle
The market is not signaling retreat. It is signaling discipline.
That distinction matters because many hydrogen opportunities remain strong. The difference is that value will increasingly accrue to projects with robust technical assumptions and policy-compatible operating models.
Several questions now deserve early review:
- Can the project document carbon intensity with enough granularity for future rule changes?
- Are materials, vessels, piping, and fueling systems aligned with recognized hydrogen safety frameworks?
- Does the business case still work if grid access, permitting, or certification takes longer than expected?
- Is the asset positioned within a broader industrial cluster, export corridor, or sovereign infrastructure plan?
The last point is becoming especially important. More policy frameworks now reward strategic fit, not isolated capacity announcements.
From that perspective, G-HEI reflects a practical market need. Decision quality improves when electrolysis, logistics, turbines, CCUS, and refueling are benchmarked as connected assets rather than separate procurement lines.
A useful response is to build optionality, not just scale
One pattern is becoming clearer in energy industry news: the best-positioned hydrogen projects are not always the largest first movers. They are often the ones designed with policy optionality.
That means preparing for changing certification rules, evolving blending limits, tighter safety inspections, and more explicit domestic content expectations.
In real project development, that can translate into modular electrolyzer design, phased storage expansion, dual-path logistics planning, and stronger traceability across equipment selection.
It also means taking standards seriously before procurement lock-in. Material compatibility, vessel performance, fueling protocol alignment, and turbine conversion assumptions should be tested early.
A sensible next step is to map each major asset against three dimensions: regulatory exposure, technical proof, and strategic relevance to the wider zero-carbon network.
That framework makes energy industry news more useful. Instead of reacting to headlines, organizations can judge whether a policy change affects revenue certainty, engineering scope, or long-term competitiveness.
Hydrogen is still a growth story, but it is no longer a loose one. The next phase belongs to projects that can connect ambition with evidence, and scale with verifiable asset security.
From here, the most effective move is not broad optimism or broad caution. It is disciplined observation, standards-led benchmarking, and a staged plan for adapting before policy shifts become project delays.
Related News
- Are Alkaline Electrolyzers Better for Remote Hydrogen Production?Sep 02, 2026Are alkaline electrolyzers better for remote hydrogen production? Explore costs, water needs, flexibility, safety, and the best fit for your site.
- How to Schedule Annual Maintenance for an Alkaline ElectrolyzerSep 01, 2026How to schedule annual maintenance for alkaline water electrolysis? Learn how to plan a safe, data-driven outage, secure critical spares, protect stack life, and ensure reliable hydrogen production.
- Is sovereign hydrogen infrastructure investment worth the long payback?Aug 15, 2026Sovereign hydrogen infrastructure investment can pay off despite long payback periods when it strengthens energy security, unlocks demand, and creates durable industrial advantage. Explore the strategic case.
- What Determines Stack Efficiency and Lifetime in an ALK Electrolysis Plant?Aug 08, 2026ALK electrolysis plant performance depends on stack materials, separator stability, electrolyte quality, temperature control, and load profile. Learn what truly drives efficiency, lifetime, and lower hydrogen cost.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.