
Is sovereign hydrogen infrastructure investment worth the long payback?




For most enterprises, sovereign hydrogen infrastructure investment is worth it only when the project is tied to a clear national or industrial advantage, not when it is treated as a generic decarbonization play. The payback period is usually long, but the strategic value can be decisive if the investment strengthens energy security, unlocks regulated demand, or protects access to future markets.
For business leaders, the real question is not whether hydrogen infrastructure is expensive. It is whether the asset will remain relevant through changing carbon rules, fuel pricing, grid constraints, and industrial policy over a 10- to 20-year horizon. That is a capital allocation question, not just an engineering one.
What this investment is really trying to solve? 
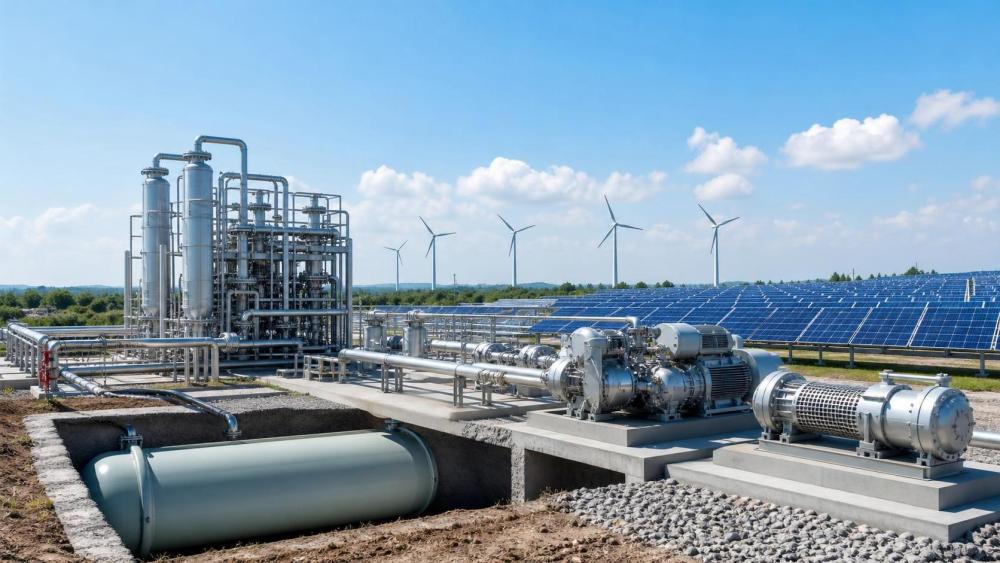
Sovereign hydrogen infrastructure investment is usually aimed at resilience, not quick financial arbitrage. It supports domestic energy security, industrial continuity, and long-term control over critical supply chains that may otherwise depend on imported fuels or volatile markets.
That matters because hydrogen infrastructure is not a single asset class. It includes production, storage, transport, conversion, and end-use equipment, each with different risk, utilization, and revenue logic. Leaders should evaluate the full chain, not isolated projects.
In practical terms, sovereign projects often justify themselves when they can serve multiple strategic roles at once: decarbonize hard-to-abate sectors, stabilize power systems, support backup fuel needs, or create a platform for exportable industrial capability. Single-purpose projects rarely clear the hurdle on their own.
Why the payback takes time
The long payback comes from high upfront capital intensity, still-maturing demand, and infrastructure that must be built before full utilization is possible. Electrolyzers, pipelines, storage caverns, compression systems, and hydrogen-ready turbines all require large early commitments.
Unlike conventional fuel infrastructure, hydrogen systems often begin with underused capacity. That is not a failure of planning; it is a feature of market formation. Early-stage assets are built ahead of demand so industrial users can switch later without starting from zero.
Cost structure also matters. Electricity price, financing terms, operating hours, and utilization rates can dominate project economics. A hydrogen asset that runs too few hours or relies on expensive power will struggle to produce acceptable returns, even if the long-term policy case is strong.
What business leaders should judge first
The first test is strategic fit. If the asset does not serve a critical industrial cluster, national energy target, or regulated reliability need, the case for sovereign funding weakens quickly. Strategic value must be concrete, not symbolic.
Next comes demand visibility. Leaders need contracted offtake, credible anchor customers, or a public-policy mechanism that reduces volume risk. Without that, long-duration infrastructure becomes a financing problem as much as a technology problem.
Then comes optionality. The best hydrogen infrastructure can support more than one use case over time, such as blending, firm power, industrial feedstock, or export logistics. Optionality improves resilience and reduces the chance of stranded capital.
Which assets deserve priority?
Not every hydrogen asset has the same business case. For many sovereign strategies, storage and transport are more defensible than speculative production alone, because they reduce system bottlenecks and enable multiple downstream applications.
Megawatt-scale electrolysis can make sense when paired with low-cost renewable power, strong grid integration, and dependable offtake. Liquid hydrogen logistics may be justified where geography or export markets demand high-density transport. Hydrogen-ready turbines are compelling when system reliability is the main objective.
High-pressure refueling infrastructure is usually more targeted. It is strongest where fleet conversion is already underway, such as buses, logistics corridors, port equipment, or industrial vehicles. Broad retail deployment without fleet density is usually too thin to pay back quickly.
CCUS infrastructure can also complement sovereign hydrogen strategies when blue hydrogen or industrial decarbonization needs a near-term bridge. The right mix depends on local resources, regulatory tolerance, and how fast the end market is expected to mature.
How to measure whether the economics are real
Decision-makers should evaluate more than simple internal rate of return. A sovereign hydrogen project may earn value through avoided fuel imports, avoided outage risk, industrial retention, carbon compliance, and future market access.
That means the evaluation framework should include scenarios for power prices, carbon prices, plant load factors, policy incentives, and utilization ramp-up. If the project only works under one optimistic assumption, it is not yet bankable.
Leaders should also separate infrastructure economics from technology optimism. The question is not whether hydrogen is important in the energy transition. The question is whether this specific asset, in this location, at this capacity, can survive the path from pilot to industrial scale.
What risks can destroy the case?
The biggest risk is stranded capacity. If demand grows too slowly, the infrastructure can sit idle while carrying heavy depreciation and financing costs. That risk is especially high when projects are built ahead of policy clarity or customer commitment.
Another risk is standards and compatibility. Hydrogen systems must align with safety, materials, and operating frameworks such as ISO 19880, ASME B31.12, and SAE J2601 where relevant. Weak technical integration can create delays, cost overruns, or unusable assets.
Policy drift is just as important. A project that depends on subsidies, tax credits, or mandated blending can lose its investment case if political priorities change. Sovereign investors need resilience against policy cycles, not dependence on them.
When the long payback is justified
The long payback is justified when hydrogen infrastructure becomes a control point for critical national capability. That includes industrial decarbonization, power system flexibility, secure fuel supply, and the ability to compete in future low-carbon trade networks.
It is also justified when the project reduces larger costs elsewhere. If hydrogen storage avoids grid instability, if hydrogen-ready generation reduces blackout exposure, or if a domestic value chain keeps strategic industries in place, the return cannot be measured on fuel margin alone.
For enterprise leaders, the most credible projects usually combine policy support, anchor demand, modular buildout, and multi-use infrastructure. Those four elements turn a long payback from a liability into a strategic asset.
In short, sovereign hydrogen infrastructure investment is worth it when the asset improves national resilience and creates durable industrial advantage, not when it is built on hope. The right decision depends on utilization, offtake, system value, and technical readiness. If those are strong, the long payback may be acceptable; if they are weak, the project should wait.
Related News
- Are Alkaline Electrolyzers Better for Remote Hydrogen Production?Sep 02, 2026Are alkaline electrolyzers better for remote hydrogen production? Explore costs, water needs, flexibility, safety, and the best fit for your site.
- How to Schedule Annual Maintenance for an Alkaline ElectrolyzerSep 01, 2026How to schedule annual maintenance for alkaline water electrolysis? Learn how to plan a safe, data-driven outage, secure critical spares, protect stack life, and ensure reliable hydrogen production.
- Is sovereign hydrogen infrastructure investment worth the long payback?Aug 15, 2026Sovereign hydrogen infrastructure investment can pay off despite long payback periods when it strengthens energy security, unlocks demand, and creates durable industrial advantage. Explore the strategic case.
- What Determines Stack Efficiency and Lifetime in an ALK Electrolysis Plant?Aug 08, 2026ALK electrolysis plant performance depends on stack materials, separator stability, electrolyte quality, temperature control, and load profile. Learn what truly drives efficiency, lifetime, and lower hydrogen cost.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.