
Building Materials Price Trends in 2026: What to Watch Before Budgeting




Building materials price trends are becoming a budgeting issue, not just a procurement issue
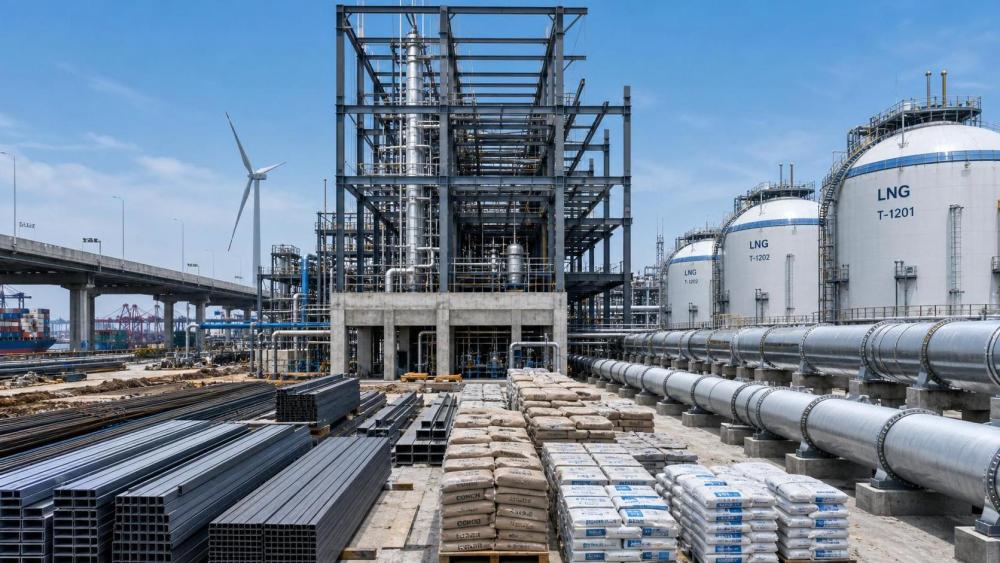
Building materials price trends in 2026 are no longer a background variable for capital planning.
They are shaping project timing, approval confidence, and the real cost of zero-carbon infrastructure.
That matters more in hydrogen, CCUS, power, and transport networks, where material performance is tied to safety, pressure, temperature, and compliance.
In that environment, building materials price trends affect more than concrete volumes or steel tonnage.
They also influence asset specification, contractor bids, contingency levels, and whether a project still clears its return threshold.
The sharper signal in 2026 is that pricing volatility is spreading from basic materials into engineered components and specialty materials.
For projects linked to electrolysis systems, cryogenic hydrogen logistics, hydrogen-ready turbines, and 70MPa refueling assets, that shift is material.
A budget that assumes stable input costs may look acceptable on paper and become fragile during detailed design.
What is changing underneath the 2026 market picture
Recent building materials price trends show a split market rather than one broad inflation wave.
Commodity materials have cooled in some regions, but specialty categories remain exposed to supply concentration and specification pressure.
That is why broad averages can be misleading during budget reviews.
Carbon steel may look manageable, while stainless grades, nickel-bearing alloys, titanium-intensive assemblies, and insulation systems still move unpredictably.
Cement pricing is another example.
In many markets, base cement costs are being reshaped by energy inputs, emissions compliance, kiln upgrades, and regional transport constraints.
So even when headline inflation appears softer, project-grade construction inputs can stay elevated.
More importantly, lead times and price validity periods have become part of the price discussion.
A quoted number with a short validity window behaves very differently from a secured supply position.
The market is now reacting to a tighter mix of cost drivers
Several forces are pushing building materials price trends at the same time, and they do not move in the same direction.
This combination explains why building materials price trends feel stickier than general inflation data would suggest.
The biggest cost pressure is moving toward performance-critical materials
In conventional construction, material substitutions are often manageable.
In hydrogen and zero-carbon assets, substitutions are narrower because pressure resistance, cryogenic behavior, corrosion tolerance, and code compliance limit flexibility.
That is where building materials price trends deserve closer interpretation.
G-HEI’s operating context makes this clear.
Megawatt-scale PEM systems, vacuum-insulated cryogenic vessels, hydrogen-ready turbine infrastructure, and high-pressure refueling systems rely on materials chosen for integrity first.
Those choices are benchmarked against standards such as ISO 19880, ASME B31.12, and SAE J2601.
As a result, cost escalation is not only about buying more material.
It is also about securing the correct grade, fabrication route, testing scope, and certified supply chain.
This has direct consequences for 2026 budgeting.
- Structural steel budgets may remain negotiable, but pressure-rated piping packages may not.
- Concrete scope can sometimes be phased, while cryogenic insulation packages usually cannot.
- Mechanical cost risk increasingly sits in specialized assemblies rather than in general site works.
That distinction is easy to miss when a budget is reviewed only at total project level.
Why the impact does not fall evenly across project stages
Building materials price trends hit projects differently at concept, FEED, EPC tender, and execution stages.
At concept stage, the main risk is false confidence.
High-level cost models often carry standard indices that understate the premium for hydrogen-ready materials.
During FEED, scope becomes more precise and the pricing gap usually widens.
By tender stage, suppliers begin pricing actual exposure to energy, alloy inputs, and qualification requirements.
Execution creates another layer.
Late design changes, inspection demands, and shipping disruptions can push installed cost above material list price movements.
That is why building materials price trends should be tracked as stage-based risk, not as a single annual assumption.
A practical way to separate signal from noise
The most useful review lens in 2026 is to divide materials into three budgeting groups.
- Stable but heavy-volume inputs, such as rebar, structural steel, and base concrete.
- Energy-sensitive processed materials, including cement, glass, insulation, and fabricated sections.
- Specification-critical materials, such as stainless systems, alloy piping, cryogenic packages, and titanium-linked assemblies.
The third group is where building materials price trends can most easily distort investment decisions.
What deserves closer attention before 2026 budgets are locked
A useful budget review now goes beyond average escalation rates.
It tests where project economics are sensitive to material integrity requirements and timing risk.
From recent building materials price trends, several questions stand out.
- Which packages depend on limited global suppliers or certified fabrication capacity?
- Where are standards forcing higher-grade materials than early models assumed?
- How much of the budget is exposed to short quote validity periods?
- What portion of contingency covers logistics, testing, and requalification rather than only raw material movement?
- Are lower-carbon material preferences introducing premiums that have not been priced transparently?
These questions matter because building materials price trends are increasingly connected to compliance and asset security.
For sovereign-scale decarbonization projects, a cheaper material path is not always an executable one.
The next move is disciplined scenario budgeting, not broad cost padding
Adding a generic contingency is a weak response when cost pressure is concentrated in a few technical packages.
A better approach is to build scenarios around the materials most exposed to 2026 market shifts.
That means pairing building materials price trends with engineering assumptions, approval gates, and supply timing.
In practice, the strongest plans tend to do four things well.
- Recast budgets around material criticality instead of broad trade categories.
- Stress-test specialty packages against delayed procurement and tighter specifications.
- Separate raw material exposure from fabrication, certification, and logistics exposure.
- Use current benchmark intelligence from hydrogen and zero-carbon infrastructure, not legacy construction averages.
This is where market observation becomes actionable.
The value is not in predicting every price move.
It is in identifying which building materials price trends could change approval outcomes, phasing choices, or capital efficiency.
For 2026, that means continuing to watch steel and cement, but looking even harder at alloys, insulation, cryogenic systems, and standards-linked fabrication.
The next sensible step is to map those exposures package by package, compare them against current benchmark data, and update budget assumptions before commitment windows narrow.
Related News
- Electricity Price Volatility Is Rewriting Hydrogen Cost ModelsApr 27, 2026Impact of electricity price on hydrogen cost is transforming industrial decarbonization and large-scale electrolysis. Explore LCOH trends, PPA strategies, and resilient hydrogen infrastructure planning.
- Energy Transition Plans Often Fail at the Grid Connection StageApr 27, 2026Sustainable energy and energy transition projects often fail at grid connection. Learn how hydrogen infrastructure, PEM electrolysis, and industrial decarbonization can avoid delays and protect investment value.
- What Is Slowing Industrial Decarbonization Projects in 2026?Apr 27, 2026Industrial decarbonization faces delays in 2026 as hydrogen infrastructure, sustainable energy access, grid limits, safety standards, and project bankability challenge the energy transition.
- How G-HEI benchmarking can reveal PEM electrolyzer reliabilitySep 07, 2026G-HEI PEM electrolyzer benchmarking reliability reveals lifecycle risks, dynamic-duty performance, safety controls, and maintainability for smarter hydrogen investments.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.