
Chemical Supply Chain Disruptions: Key Risks and Cost Impacts in 2026




Chemical Supply Chain Disruptions: Key Risks and Cost Impacts in 2026
The phrase chemicals supply chain disruptions is often treated as a procurement problem: a late shipment, an unexpected surcharge, a supplier that suddenly cannot confirm lead time. In 2026, that reading is too narrow. For hydrogen infrastructure, CCUS assets, industrial gas systems, and other capital-intensive energy projects, chemical disruption now behaves more like a system-level constraint. It affects not only input prices, but commissioning schedules, materials qualification, maintenance intervals, insurance assumptions, and in some cases the technical viability of a project design.
That matters because many assets in the zero-carbon transition depend on chemicals that are easy to overlook until they are missing. Electrolyzers require treated water chemistries, membranes, catalysts, cleaning agents, and specialty coatings. Cryogenic hydrogen logistics rely on insulation systems, sealants, process gases, and material-treatment chemistries. High-pressure refueling systems and hydrogen-compatible piping are tied to lubricants, testing media, corrosion-control chemicals, polymers, and surface-preparation inputs. None of these categories gets the same board-level attention as turbines, compressors, or storage vessels, yet delays in them can hold up the same final investment decision.
The real issue is that “chemicals” in industrial projects are not a single market. They sit across basic petrochemicals, industrial gases, catalysts, solvents, resins, treatment additives, fluorinated materials, coatings, and highly regulated specialty formulations. Some are globally traded commodities. Others are effectively single-source, or depend on a small group of qualified plants because contamination control, safety compliance, or performance tolerances are tight. When executives hear that the chemicals market is under pressure, they need to ask a more operational question: which chemistry, qualified for which use case, under which regulatory or engineering constraint?
Why 2026 Looks Different
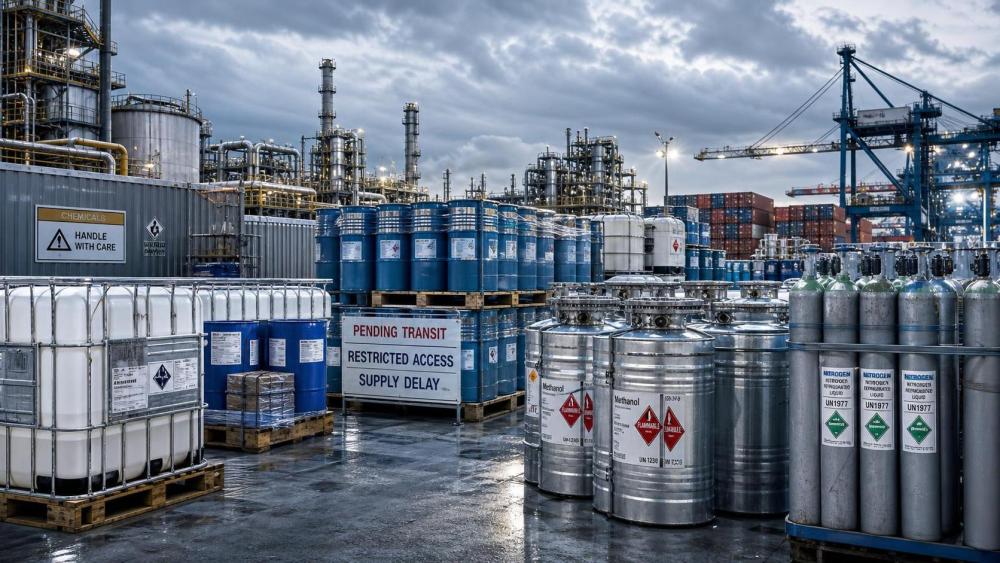
Disruptions are not new. What is different in 2026 is the way several pressures now stack on top of one another. Geopolitical fragmentation has made feedstock routing less predictable. Energy-intensive chemical production remains exposed to power and gas price volatility in several regions. At the same time, decarbonization programs are increasing demand for specialty materials that already had limited manufacturing depth. Add stricter transport rules for hazardous substances, insurance conservatism, and port congestion affecting dangerous goods handling, and the old assumption of interchangeable supply starts to break down.
For hydrogen-related projects, another layer appears: technical qualification. A replacement chemical cannot always be swapped in like a commodity bolt. If the substance is part of a cleaning protocol, membrane environment, pressure-seal system, or cryogenic assembly process, even a near-equivalent may require engineering review, compatibility assessment, or revalidation against internal standards. In regulated operations, that review cycle has its own cost. The disruption is no longer only in logistics; it migrates into quality assurance and project governance.
This is where many cost models fail. They capture inflation in purchased materials, but not the secondary cost of redesign, retesting, contract variation, delayed turnover, or a mismatch between long-lead equipment arrival and consumables readiness. For major infrastructure programs, those indirect effects can matter more than the invoice increase itself.
The Risk Is Not Just Higher Prices
When decision-makers discuss disruption, they often focus on unit cost escalation. That is only one layer. The more consequential exposures usually sit in four areas.
Notice what is missing from that table: simple volume shortage. In many real industrial settings, the problem is not absolute unavailability. It is unreliable access to the exact grade, packaging format, documentation package, or approved source needed for a specific plant environment. That distinction shapes how companies should respond.
Where the Pressure Shows Up First
In broad industrial terms, supply stress tends to surface first in categories with one or more of these traits: energy-intensive production, dependence on a narrow feedstock base, hazardous transport complexity, or long qualification cycles. For hydrogen-economy infrastructure, several categories deserve closer attention even when public market commentary is focused elsewhere.
One is high-purity and performance-sensitive chemistry. Electrolysis and gas processing systems can be unforgiving where purity, trace contamination, or membrane interaction is concerned. Another is polymer and fluoropolymer-linked supply, because sealing, lining, and chemical-resistance performance often rely on materials that are not trivial to replace. Coatings and surface-treatment chemistries are another blind spot. They may look secondary in the capex stack, but corrosion protection, cleanliness control, and storage readiness can hinge on them. Industrial gases also belong in this discussion, even if many executives instinctively separate them from “chemicals.” In practice, they sit inside the same vulnerability map because distribution networks, cylinder logistics, and purity assurance all affect project continuity.
A common mistake is to assume that large EPC contracts absorb this complexity. They may absorb some of it commercially. They do not eliminate physical bottlenecks. If a qualified chemical input is constrained upstream, someone still carries the delay. The question is whether it appears as a visible procurement issue early enough to manage, or as a late-stage execution shock after mobilization has already begun.
Why Hydrogen and CCUS Projects Are Especially Exposed
Hydrogen and carbon-management infrastructure sit at an awkward intersection: they are strategic enough to move quickly, but technically sensitive enough that material substitutions can trigger caution. Hydrogen service raises well-known concerns around embrittlement, leakage control, sealing integrity, purity management, and pressure-cycle durability. CCUS systems bring their own corrosion, solvent handling, dehydration, and process compatibility demands. Even where the critical hardware gets most of the engineering scrutiny, the enabling chemicals around those systems carry real operational weight.
This is also why standards matter indirectly. Frameworks such as ISO 19880 for hydrogen fueling, ASME B31.12 for hydrogen piping and pipelines, and SAE J2601 for fueling protocols do not function as shopping lists for chemicals. But they shape the operating envelope in which materials, maintenance practices, and system components must perform. Once a project is designed against those rigorous conditions, tolerance for ad hoc substitution narrows. A cheaper or more available input may still be unacceptable if it creates uncertainty around cleanliness, compatibility, or long-term integrity.
For sovereign-scale energy programs, this becomes a strategic question rather than a purchasing detail. A nation can secure electrolyzer capacity on paper and still face schedule erosion if the supporting material ecosystem is shallow, geographically concentrated, or weakly qualified.
The Misread That Leads to Bad Decisions
One persistent misunderstanding is to equate diversification with resilience in every case. Multi-sourcing helps when specifications are broad and qualification is mature. It helps far less when the approved supplier list is narrow for technical reasons. In those situations, forcing additional vendors into the chain can create administrative comfort without reducing actual risk.
Another misread is treating chemical inventories like a universal hedge. Stockpiling can protect maintenance continuity, but it can also create shelf-life issues, hazardous storage burdens, insurance complications, and working-capital drag. The smarter question is not “how much extra should we buy?” but “which inputs have asymmetric disruption impact, and what is the real cost of being short?” For some items, dual qualification may matter more than volume buffer. For others, regional warehousing or revised incoterms may reduce exposure more effectively than carrying months of stock.
There is also a tendency to assume that procurement can solve this alone. It cannot. In 2026, managing chemicals supply chain disruptions requires a tighter loop among engineering, operations, quality, HSE, legal, and treasury. The finance side needs visibility because volatile inputs alter not only budget forecasts but also payment timing, contingencies, and covenant-sensitive project cash flow. The technical side needs visibility because late substitutions can compromise maintainability long after handover.
What Decision-Makers Should Actually Track
For enterprise planning, broad market headlines are useful only up to a point. Better signals tend to be more granular:
- whether critical inputs rely on a single qualified formulation or a truly interchangeable family of products;
- how much of the cost exposure comes from transport, hazard handling, and compliance rather than factory-gate price;
- where the project schedule contains chemical-dependent gating events such as cleaning, testing, passivation, insulation work, water-treatment startup, or fueling-system validation;
- which substitutions would trigger internal reapproval, third-party review, or customer sign-off;
- how exposed the supplier base is to regional energy costs, export controls, transport restrictions, or environmental permitting constraints.
Those indicators do not produce a simple market forecast, but they are more useful than generic inflation assumptions. They tell management where a supply disturbance becomes a schedule disturbance, and where a schedule disturbance becomes a capital-efficiency problem.
By 2026, chemicals supply chain disruptions should be read less as an episodic procurement annoyance and more as a test of industrial preparedness. In hydrogen, CCUS, cryogenic logistics, and high-pressure fueling, the projects that stay on track will not necessarily be the ones paying the lowest spot price. They will be the ones that understand which chemical dependencies are technically non-negotiable, which are commercially flexible, and which deserve board-level attention before the next shortage makes that distinction painfully expensive.
Related News
- Electricity Price Volatility Is Rewriting Hydrogen Cost ModelsApr 27, 2026Impact of electricity price on hydrogen cost is transforming industrial decarbonization and large-scale electrolysis. Explore LCOH trends, PPA strategies, and resilient hydrogen infrastructure planning.
- Energy Transition Plans Often Fail at the Grid Connection StageApr 27, 2026Sustainable energy and energy transition projects often fail at grid connection. Learn how hydrogen infrastructure, PEM electrolysis, and industrial decarbonization can avoid delays and protect investment value.
- What Is Slowing Industrial Decarbonization Projects in 2026?Apr 27, 2026Industrial decarbonization faces delays in 2026 as hydrogen infrastructure, sustainable energy access, grid limits, safety standards, and project bankability challenge the energy transition.
- How G-HEI benchmarking can reveal PEM electrolyzer reliabilitySep 07, 2026G-HEI PEM electrolyzer benchmarking reliability reveals lifecycle risks, dynamic-duty performance, safety controls, and maintainability for smarter hydrogen investments.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.