
Foreign Trade Policy Shifts That May Reshape Industrial Sourcing in 2026




Foreign trade policy is no longer a background issue in 2026
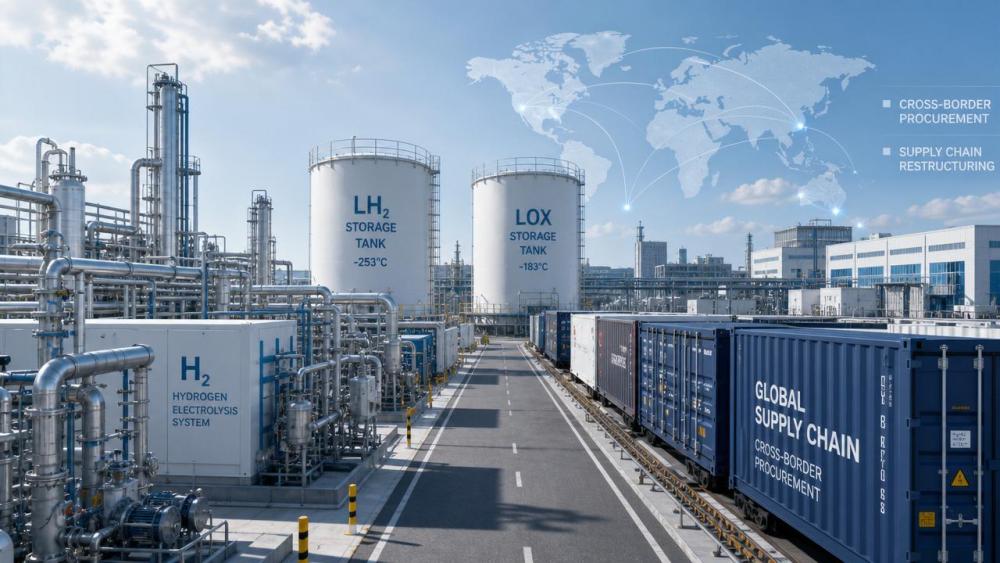
Industrial sourcing in 2026 is being reshaped by foreign trade policy at a speed few sectors expected two years ago.
What once looked like a customs or tariff question now reaches deep into plant design, supplier qualification, logistics strategy, and capital planning.
The shift is especially visible across hydrogen, zero-carbon infrastructure, and high-performance industrial systems where technical risk and geopolitical risk now move together.
Foreign trade policy is shaping which electrolyzer components move freely, which cryogenic vessels face extra scrutiny, and which hydrogen-ready turbines qualify for public support.
That matters because the energy transition has entered an execution phase.
Large-scale projects no longer depend only on engineering feasibility.
They depend on whether cross-border sourcing can satisfy origin rules, subsidy conditions, material traceability, and sovereign energy-security priorities.
In this environment, foreign trade policy becomes a board-level variable rather than a downstream compliance task.
For organizations working with megawatt-scale electrolysis, liquid hydrogen logistics, CCUS assets, or high-pressure fueling systems, the cost of misreading policy is rising quickly.
The market signals are becoming clearer than the headlines
Recent changes suggest that foreign trade policy is moving beyond broad protectionism into a more selective industrial filter.
Governments are not simply blocking imports.
They are steering supply chains toward strategic technologies, preferred jurisdictions, and approved standards frameworks.
This becomes obvious in sectors tied to grid stability, decarbonization, transport fuels, and industrial resilience.
Hydrogen infrastructure sits at the center of that overlap.
A titanium-based PEM stack, a vacuum-insulated cryogenic tank, or a 70MPa refueling assembly is no longer assessed only on price and lead time.
Its sourcing pathway now carries policy meaning.
More deals are being evaluated through three connected questions: where the asset is made, what standards it satisfies, and whether its supply chain can withstand policy shocks.
This is why foreign trade policy now influences equipment selection earlier in project development.
The strongest signals now appearing in industrial sourcing
- Tariffs are becoming more targeted around strategic materials, clean-energy equipment, and dual-use industrial technologies.
- Local-content rules are tightening access to grants, tax credits, and public infrastructure tenders.
- Compliance expectations now include origin disclosure, carbon data, and material-integrity documentation.
- Cross-border approvals increasingly depend on safety alignment with standards such as ISO 19880, ASME B31.12, and SAE J2601.
- Export controls are affecting specialized valves, controls, membranes, alloys, and precision process equipment.
Taken together, these signals show that foreign trade policy is now filtering not only trade volumes, but also technology pathways.
Why this policy turn is becoming harder to reverse
Several forces are reinforcing one another.
That is why the current shift looks structural rather than temporary.
One driver is energy sovereignty.
Countries want decarbonization without creating a new dependency on fragile external supply networks.
Another is subsidy competition.
Public money is now tied to domestic capability, trusted partners, and visible industrial spillover.
A third factor is technology sensitivity.
Hydrogen and zero-carbon assets combine strategic infrastructure, advanced materials, and safety-critical engineering.
That combination naturally attracts stronger foreign trade policy oversight.
More importantly, these drivers reinforce project financing decisions.
Once lenders and public authorities price in foreign trade policy risk, market behavior changes even faster.
The impact is spreading across more than one industrial layer
The first effect appears in equipment procurement, but it does not stop there.
Foreign trade policy is influencing design choices, supplier audits, spare-parts planning, and even commissioning timelines.
For electrolysis systems, imported membranes, catalysts, power electronics, and titanium assemblies may face policy-linked cost swings or approval delays.
For cryogenic hydrogen logistics, pressure on insulated vessels, specialty metals, and transport hardware can reshape route economics.
For hydrogen-ready gas turbines, foreign trade policy may alter access to burners, control systems, and retrofitting packages.
CCUS infrastructure also feels the change through compressors, pipe materials, monitoring systems, and permitting expectations.
What is changing, then, is not only where equipment comes from.
It is how entire projects are sequenced and de-risked.
Areas where policy friction now shows up earlier
- Front-end engineering decisions that depend on component origin and certifiable substitutions.
- Contract terms covering tariff adjustment, export restrictions, and documentation liability.
- Inventory strategy for safety-critical parts with long approval cycles.
- Bid competitiveness when subsidy rules favor domestic assembly or strategic allies.
- Insurance and financing reviews where foreign trade policy is treated as execution risk.
This broader effect explains why sourcing teams alone cannot absorb the issue.
The response has to connect commercial, engineering, legal, and policy intelligence.
Technical credibility is becoming a trade advantage, not just an engineering virtue
A notable development in 2026 is the closer link between foreign trade policy and technical assurance.
Authorities and investors increasingly want evidence that imported or cross-border assets can perform safely across full operating conditions.
That gives more weight to benchmark-driven evaluation.
In hydrogen and zero-carbon infrastructure, reference frameworks matter because the equipment is expensive, sensitive, and highly regulated.
This is where repositories such as G-HEI become more strategically relevant.
Not as marketing catalogues, but as decision support for technical comparability, standards alignment, and asset-security judgement.
When foreign trade policy tightens, the market rewards assets supported by stronger traceability, materials evidence, and compliance clarity.
That is particularly true for projects involving ISO 19880 fueling requirements, ASME B31.12 piping considerations, or SAE J2601 fueling consistency.
The practical implication is straightforward.
In a fragmented trade environment, technical benchmarking can reduce commercial uncertainty.
What deserves closer attention over the next planning cycle
The next twelve months are unlikely to produce a single global rulebook.
A more realistic expectation is a layered market where foreign trade policy differs by corridor, asset class, and strategic importance.
That means monitoring only tariffs is no longer enough.
The better approach is to watch combinations of signals.
- Changes in subsidy eligibility that indirectly redefine acceptable sourcing structures.
- Updates to customs classifications affecting hydrogen equipment, balance-of-plant systems, and critical materials.
- New disclosure requirements around origin, embodied carbon, and strategic content.
- Regional safety enforcement that raises the value of certifiable substitutes.
- Lead-time divergence between politically favored and politically exposed supply routes.
From a strategic standpoint, foreign trade policy should now be read as a market design tool.
It influences who scales, which technologies localize, and where infrastructure clusters are likely to accelerate.
A practical response starts with better visibility, not bigger slogans
The most resilient organizations are not necessarily those with the largest supplier base.
They are the ones that understand how foreign trade policy interacts with technical standards, funding structures, and project sequencing.
That usually begins with a clear map of policy-sensitive components across the asset lifecycle.
It also requires comparing suppliers on more than unit cost.
Origin exposure, substitution feasibility, standards support, and documentation depth now matter just as much.
For hydrogen and zero-carbon infrastructure, it is wise to review where single-point dependency remains hidden inside critical subsystems.
That review should cover electrolyzer stacks, cryogenic storage hardware, turbine conversion packages, compression systems, and fueling assemblies.
A sensible next step is to build a staged response plan.
Track policy signals by region, test substitute pathways against required standards, and align sourcing decisions with long-horizon infrastructure goals.
In 2026, foreign trade policy is not just changing trade.
It is quietly redrawing the industrial map behind the energy transition.
Those who respond early will be better positioned to protect delivery certainty, preserve technical integrity, and capture value as the hydrogen frontier scales.
Related News
- Electricity Price Volatility Is Rewriting Hydrogen Cost ModelsApr 27, 2026Impact of electricity price on hydrogen cost is transforming industrial decarbonization and large-scale electrolysis. Explore LCOH trends, PPA strategies, and resilient hydrogen infrastructure planning.
- Energy Transition Plans Often Fail at the Grid Connection StageApr 27, 2026Sustainable energy and energy transition projects often fail at grid connection. Learn how hydrogen infrastructure, PEM electrolysis, and industrial decarbonization can avoid delays and protect investment value.
- What Is Slowing Industrial Decarbonization Projects in 2026?Apr 27, 2026Industrial decarbonization faces delays in 2026 as hydrogen infrastructure, sustainable energy access, grid limits, safety standards, and project bankability challenge the energy transition.
- How G-HEI benchmarking can reveal PEM electrolyzer reliabilitySep 07, 2026G-HEI PEM electrolyzer benchmarking reliability reveals lifecycle risks, dynamic-duty performance, safety controls, and maintainability for smarter hydrogen investments.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.