How to Compare Hydrogen Production Infrastructure Suppliers in 2026




Why supplier comparison has changed in 2026
Hydrogen investment decisions now sit closer to national infrastructure planning than to ordinary equipment procurement.
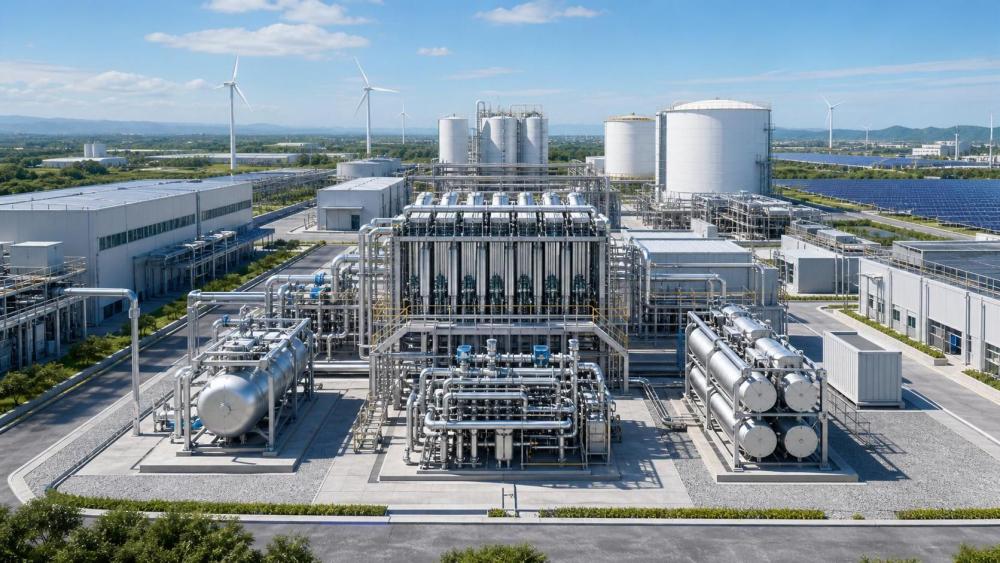
That shift explains why hydrogen production infrastructure suppliers are being assessed with far more discipline than even two years ago.
Projects are larger, financing is tighter, and operating risk is no longer confined to the production skid.
A supplier choice now affects grid integration, storage design, transport interfaces, insurance terms, and future export readiness.
In practical terms, comparing suppliers means comparing technical credibility across the full zero-carbon chain.
That is where benchmarking frameworks such as G-HEI have become useful reference points.
They connect electrolysis output with material integrity, safety rules, and long-horizon asset performance.
For decision-making, this creates a better question than who offers the lowest quote.
The better question is which hydrogen production infrastructure suppliers can support sovereign-grade scale without creating hidden technical debt.
What counts as production infrastructure
The term covers more than electrolyzers.
It includes balance-of-plant engineering, compression, purification, cooling, storage interfaces, control systems, and safety architecture.
For many projects, utility connection and digital monitoring matter just as much as stack performance.
That broader view is essential when comparing hydrogen production infrastructure suppliers, especially across regions with different grid, water, and permitting conditions.
A credible supplier should explain where its responsibility starts and ends.
Some deliver core equipment only.
Others provide integrated packages that connect production with liquid hydrogen logistics, refueling systems, or hydrogen-ready power assets.
The distinction matters because integration gaps often become the costliest part of execution.
The comparison criteria that matter most
A serious supplier review usually becomes clearer when it is built around a few non-negotiable dimensions.
Technology maturity
In 2026, maturity is not a marketing label.
It should be visible in installed base, uptime history, degradation data, and performance under variable renewable input.
PEM and alkaline systems differ in response profile, material needs, and operating economics.
A supplier should show where each platform performs best, rather than claiming a universal fit.
Safety and compliance depth
Safety cannot be reviewed only through certificates.
The stronger hydrogen production infrastructure suppliers demonstrate how design choices align with ISO 19880, ASME B31.12, SAE J2601, and local code pathways.
That includes shutdown logic, venting strategy, leak detection, hazardous area classification, and operator training support.
Material integrity
Hydrogen service exposes weak material decisions quickly.
Embrittlement resistance, sealing quality, corrosion behavior, and cryogenic compatibility all influence asset life.
This is particularly relevant where high-pressure compression or liquid hydrogen pathways are planned later.
Scalability and modularity
Many projects begin with one capacity target and expand within three years.
Suppliers should be judged on how cleanly they scale modules, controls, utilities, and maintenance regimes.
Expansion should not require redesigning the entire plant backbone.
Lifecycle economics
Capex still matters, but it no longer decides the ranking alone.
Electricity consumption, stack replacement intervals, water treatment needs, maintenance access, and spare part availability shape the real cost curve.
Where supplier differences show up in real projects
The best comparisons come from actual operating scenarios, not brochure claims.
An ammonia export project, a steel decarbonization hub, and a 70MPa refueling network may all buy hydrogen production systems.
They do not need the same supplier profile.
For industrial feedstock use, purity consistency and continuous output may dominate.
For mobility corridors, compression reliability and fueling compatibility rise in priority.
For power balancing, dynamic response and turbine integration become more important.
This is one reason G-HEI’s cross-chain perspective matters.
Production cannot be evaluated in isolation from cryogenic logistics, gas turbine readiness, CCUS adjacency, or refueling architecture.
Strong hydrogen production infrastructure suppliers understand downstream consequences and design upstream equipment accordingly.
Questions that reveal supplier quality faster
A short list of precise questions often exposes more than a thick proposal package.
- What operating data can be shared from comparable capacity, climate, and duty cycle conditions?
- Which components are most likely to limit output over five years, and what is the replacement strategy?
- How is the system configured for pressure, purity, and future storage pathway changes?
- Which standards are addressed by design, and which depend on project-specific engineering?
- What portion of maintenance can be handled locally, and what remains vendor-dependent?
- How does the control system manage renewable intermittency without accelerating stack degradation?
Suppliers with robust answers usually speak in data ranges, failure modes, and operational tradeoffs.
Weaker vendors tend to stay at headline efficiency numbers.
Common mistakes in supplier evaluation
One frequent mistake is comparing only nameplate output.
Another is treating all hydrogen production infrastructure suppliers as interchangeable once basic certifications are present.
That assumption usually fails during commissioning or scale-up.
A third mistake is separating technical diligence from commercial diligence.
Warranty language, performance guarantees, spare part commitments, and upgrade rights deserve the same attention as stack chemistry.
There is also a timing issue.
A supplier that looks cost-effective at bid stage may become expensive when local code adaptation, utility redesign, and service mobilization are included.
Building a practical decision framework
A useful approach is to score suppliers across technical, operational, and strategic fit.
Technical fit covers efficiency, durability, compliance depth, and material selection.
Operational fit covers maintainability, controls, integration effort, and service response.
Strategic fit covers scaling path, localization potential, financing credibility, and alignment with long-term hydrogen network design.
This structure makes it easier to compare hydrogen production infrastructure suppliers without reducing the decision to a single metric.
It also creates a defensible record for boards, investors, and public stakeholders.
A sensible next step
Start by defining the operating scenario before issuing a broad request for proposals.
Then map supplier claims against standards, integration boundaries, and lifecycle assumptions.
The organizations that compare hydrogen production infrastructure suppliers well in 2026 are not just buying equipment.
They are shaping resilient hydrogen systems, where production performance, safety architecture, and future expansion remain technically coherent from day one.
Related News
- Electricity Price Volatility Is Rewriting Hydrogen Cost ModelsApr 27, 2026Impact of electricity price on hydrogen cost is transforming industrial decarbonization and large-scale electrolysis. Explore LCOH trends, PPA strategies, and resilient hydrogen infrastructure planning.
- Energy Transition Plans Often Fail at the Grid Connection StageApr 27, 2026Sustainable energy and energy transition projects often fail at grid connection. Learn how hydrogen infrastructure, PEM electrolysis, and industrial decarbonization can avoid delays and protect investment value.
- What Is Slowing Industrial Decarbonization Projects in 2026?Apr 27, 2026Industrial decarbonization faces delays in 2026 as hydrogen infrastructure, sustainable energy access, grid limits, safety standards, and project bankability challenge the energy transition.
- How G-HEI benchmarking can reveal PEM electrolyzer reliabilitySep 07, 2026G-HEI PEM electrolyzer benchmarking reliability reveals lifecycle risks, dynamic-duty performance, safety controls, and maintainability for smarter hydrogen investments.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.