
Investment Trends in Green Hydrogen Systems for 2026




Why investment trends in green hydrogen systems look different in 2026
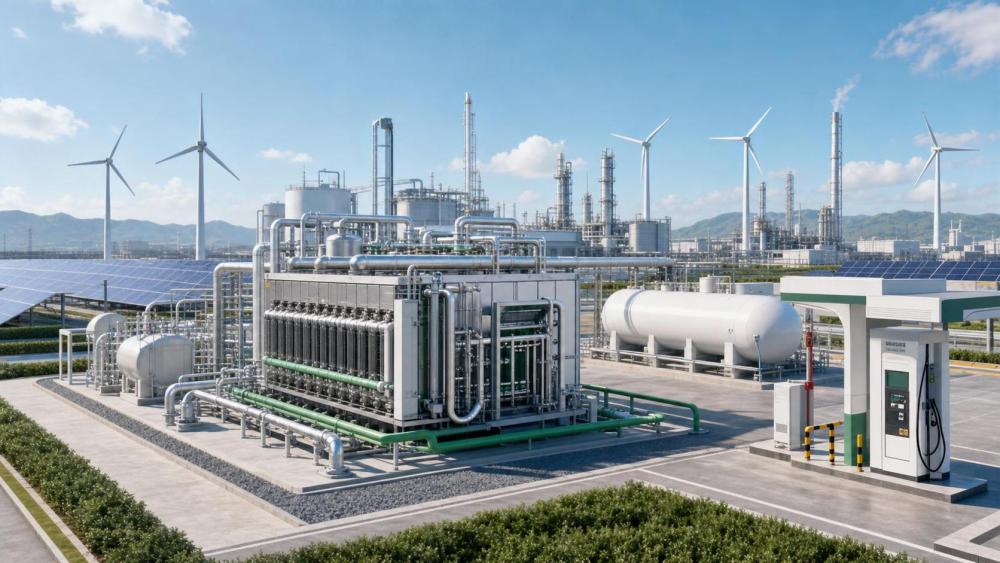
Investment trends in green hydrogen systems have moved beyond pilot enthusiasm and into infrastructure discipline.
The shift is no longer driven only by climate targets.
Energy sovereignty, grid resilience, and industrial competitiveness now shape where capital is committed.
That changes the conversation from “Can hydrogen scale?” to “Which assets can scale safely, efficiently, and under bankable standards?”
Across power, transport, heavy industry, and logistics, investment trends are becoming more selective.
Money is still flowing, but it is flowing toward systems that solve integration risk.
This includes megawatt-scale electrolysis, cryogenic handling, hydrogen-ready turbines, CCUS-linked industrial clusters, and 70MPa refueling networks.
A visible signal in 2026 is that investors increasingly treat green hydrogen as a connected infrastructure stack, not a standalone production technology.
That broader view aligns with the role of G-HEI.
Its benchmarking model reflects a market where technical performance, material integrity, and international compliance are inseparable from financial return.
The strongest market signal is a shift from capacity headlines to asset quality
Recent announcements still emphasize gigawatt ambition, yet capital committees are asking harder questions.
They want stack durability, water strategy, storage losses, boil-off control, pipeline compatibility, and dispatch economics.
This is why investment trends now favor fewer speculative projects and more technically verified platforms.
In practical terms, premium valuation is moving toward assets with clearer operating envelopes.
PEM systems with titanium-based components, advanced ALK configurations, and modular balance-of-plant designs attract stronger attention.
The same applies to vacuum-insulated cryogenic vessels and hydrogen-blending turbine retrofits.
What matters is not novelty alone.
What matters is whether the technology can survive procurement scrutiny, permitting delays, and long-term maintenance realities.
Where that selectivity is becoming visible
- Electrolysis projects are judged by load flexibility, stack replacement intervals, and downstream compression economics.
- Hydrogen logistics projects are screened for insulation performance, transport density, and handling safety under real operating conditions.
- Power applications are evaluated by blending limits, turbine metallurgy, and dispatch compatibility with grid volatility.
- Refueling infrastructure is assessed through throughput reliability, fill protocol compliance, and station uptime economics.
Why sovereign priorities are reshaping investment trends
One reason investment trends are changing is that hydrogen is now tied to national resilience.
Fuel import exposure, transmission bottlenecks, and geopolitical supply shocks have raised the value of controllable domestic energy systems.
Green hydrogen fits this logic when paired with renewable overbuild, storage, and industrial demand anchors.
Another driver is decarbonization pressure in sectors that cannot electrify easily.
Steel, chemicals, shipping fuels, backup power, and long-haul mobility require molecules, not only electrons.
That creates durable demand for hydrogen systems built around performance certainty.
There is also a regulatory layer.
Standards such as ISO 19880, ASME B31.12, and SAE J2601 are no longer technical footnotes.
They increasingly influence financing timelines, insurer confidence, and cross-border project bankability.
The value chain is no longer moving at the same speed
A common mistake is to read investment trends as if every hydrogen segment matures together.
That is not what 2026 shows.
Electrolysis capacity attracts headlines, yet logistics, storage, and end-use conversion are becoming the real gating factors.
This uneven pace has strategic consequences.
Projects that ignore cryogenic distribution, compression needs, or turbine compatibility may secure early funding but struggle to reach durable utilization.
More mature capital now prefers corridor thinking.
It looks at production, transport, storage, and demand as one operating chain.
This is where G-HEI’s five-pillar perspective becomes useful.
Benchmarking isolated components is no longer enough when system bottlenecks determine project value.
Segments drawing the clearest momentum
Megawatt-scale electrolysis remains central, especially where renewable curtailment creates low-cost power windows.
Cryogenic liquid hydrogen logistics are gaining importance because storage density and transport economics now shape regional viability.
Hydrogen-ready gas turbines are also moving up the agenda.
They offer a practical route for balancing intermittent renewable supply within existing power structures.
Meanwhile, high-pressure refueling systems benefit where commercial mobility transitions require predictable fueling performance, not experimental infrastructure.
The biggest returns may come from de-risking, not just scaling
The most important reading of current investment trends is that risk engineering has become a growth category.
In earlier phases, capital often rewarded first movers.
In 2026, it increasingly rewards operators who can document survivability across safety, maintenance, materials, and throughput.
That favors benchmark-led decision models.
A project with lower nominal capacity can outperform a larger competitor if its compliance pathway is clearer and its integration losses are lower.
More deal teams now examine questions that were once left to engineers late in the process.
- Can vessel insulation maintain economics across transport cycles?
- Will stack chemistry support duty-cycle variability without accelerated degradation?
- Does turbine retrofitting create hidden material or emissions trade-offs?
- Are refueling protocols aligned with future fleet utilization, not only current demand?
These questions explain why investment trends increasingly reward technical transparency.
What deserves attention before the next round of capital commitments
The near-term outlook is constructive, but not uniform.
Projects connected to strong offtake, compliant infrastructure, and measurable operating benchmarks should remain the most resilient.
Projects built around isolated capacity claims may face slower approvals and weaker financing terms.
A practical response begins with sharper screening criteria.
Review asset choices against end-use pathways, standards exposure, replacement intervals, and network compatibility.
Compare electrolyzer performance with logistics constraints, not in isolation.
Track how ISO 19880, ASME B31.12, and SAE J2601 affect deployment timing and insurance confidence.
Use benchmark repositories such as G-HEI to test whether high-performance claims translate into asset security over time.
The next phase of investment trends in green hydrogen systems will likely reward disciplined sequencing.
The strongest positions will come from linking production, transport, storage, and end use before bottlenecks become expensive.
That makes the immediate next step clear: refine scenario assumptions, compare system-level benchmarks, and build a phased response plan around compliant infrastructure rather than headline capacity alone.
Related News
- Electricity Price Volatility Is Rewriting Hydrogen Cost ModelsApr 27, 2026Impact of electricity price on hydrogen cost is transforming industrial decarbonization and large-scale electrolysis. Explore LCOH trends, PPA strategies, and resilient hydrogen infrastructure planning.
- Energy Transition Plans Often Fail at the Grid Connection StageApr 27, 2026Sustainable energy and energy transition projects often fail at grid connection. Learn how hydrogen infrastructure, PEM electrolysis, and industrial decarbonization can avoid delays and protect investment value.
- What Is Slowing Industrial Decarbonization Projects in 2026?Apr 27, 2026Industrial decarbonization faces delays in 2026 as hydrogen infrastructure, sustainable energy access, grid limits, safety standards, and project bankability challenge the energy transition.
- How G-HEI benchmarking can reveal PEM electrolyzer reliabilitySep 07, 2026G-HEI PEM electrolyzer benchmarking reliability reveals lifecycle risks, dynamic-duty performance, safety controls, and maintainability for smarter hydrogen investments.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.