
Manufacturing Market Updates: 2026 Signals Reshaping Hydrogen Projects




Manufacturing market updates in 2026 are no longer a side note for hydrogen projects. They now shape timing, financing, engineering scope, and national energy positioning across the full zero-carbon chain.
The latest shifts are especially visible where electrolysis capacity, cryogenic transport, hydrogen-ready turbines, and CCUS assets intersect. In practical terms, project success depends less on ambition alone and more on standards discipline, supply resilience, and asset integrity.
That is why manufacturing market updates matter beyond factory output. They reveal how equipment availability, materials performance, compliance pathways, and sovereign infrastructure priorities are reshaping hydrogen investment decisions.
Why 2026 feels different for hydrogen manufacturing
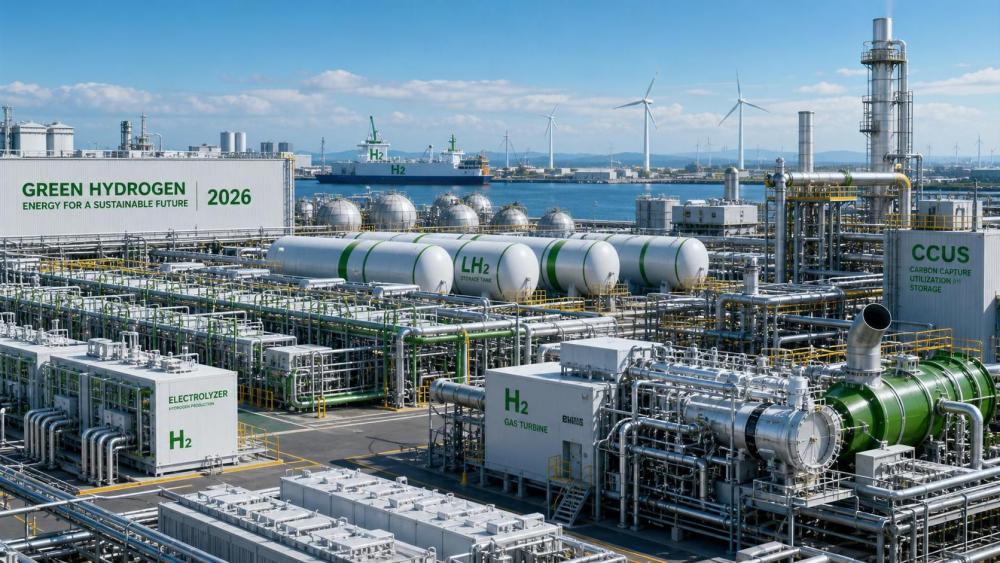
Hydrogen has moved from pilot enthusiasm to system-level execution. That transition changes what decision quality looks like. Market visibility now needs to extend from component metallurgy to export corridor readiness.
Earlier market cycles rewarded scale announcements. The current phase rewards validated deliverability. This includes stack durability, vessel insulation performance, pipeline compatibility, refueling safety, and turbine conversion confidence.
Manufacturing market updates therefore act as an early warning system. They show where lead times are tightening, where certification bottlenecks are emerging, and where technical specifications are becoming non-negotiable.
For cross-border hydrogen strategies, another layer matters. Countries are increasingly linking industrial policy with energy sovereignty, meaning local production capability and standards alignment now influence project bankability.
What the current signals are really saying
Not every update carries the same weight. In 2026, the most useful manufacturing market updates are the ones that connect equipment trends with operational risk and infrastructure readiness.
Electrolysis is entering a performance-driven phase
Megawatt-scale PEM and alkaline systems are still central, but focus has shifted. Buyers are comparing balance-of-plant reliability, stack replacement assumptions, water quality tolerance, and energy efficiency under real operating conditions.
Manufacturing market updates now highlight a more selective market. Capacity additions still matter, yet technical consistency and serviceability matter more when projects move from demonstration to sovereign-scale deployment.
Cryogenic logistics is becoming a strategic bottleneck
Liquid hydrogen transport depends on specialized vessels, insulation systems, and loss-control design. Small deviations in manufacturing quality can translate into significant cost, safety, and delivery issues at scale.
This is one reason manufacturing market updates are watched closely across ports, storage hubs, and export chains. The market is rewarding suppliers that can prove thermal performance, material integrity, and repeatable fabrication quality.
Power and CCUS are converging with hydrogen planning
Hydrogen-ready gas turbines and CCUS infrastructure are no longer treated as separate planning tracks. They increasingly sit inside the same capital discussion about dispatchable low-carbon energy and industrial decarbonization.
The important signal is not just technology maturity. It is integration maturity, including fuel flexibility, retrofit feasibility, carbon transport logistics, and exposure to evolving compliance requirements.
Where standards now influence commercial outcomes
One of the clearest themes in manufacturing market updates is that standards have moved from background compliance to front-line commercial criteria. This is particularly true in hydrogen infrastructure.
Frameworks such as ISO 19880, ASME B31.12, and SAE J2601 increasingly shape procurement, insurance posture, permitting speed, and long-term operational confidence. A project that misses standards readiness often absorbs delays later.
That is where a benchmarking environment like G-HEI becomes relevant. Its value is not promotional language. Its value lies in helping stakeholders compare assets against technical, safety, and material-integrity thresholds that matter in real deployment.
For example, titanium-based PEM stacks, vacuum-insulated cryogenic vessels, and hydrogen-blending turbines cannot be assessed on price alone. Their performance envelope must be understood against international operating expectations.
How manufacturing market updates translate into business value
At a practical level, manufacturing market updates help organizations avoid two common mistakes. One is overcommitting to scale without verifying component maturity. The other is underestimating how infrastructure dependencies compound delay risk.
The business value comes from sharper sequencing. When market intelligence is tied to standards and asset performance, capital can be phased more intelligently across production, storage, transport, power conversion, and end-use delivery.
This is especially important in integrated hydrogen programs. A strong electrolyzer package cannot compensate for weak cryogenic logistics. A compliant refueling design does not solve turbine fuel issues upstream. The chain has to work as a system.
For that reason, the best manufacturing market updates are multidisciplinary. They combine market movement with engineering evidence, operating constraints, and benchmarked compliance expectations.
The project areas drawing the closest attention
Several segments are attracting stronger scrutiny because they sit at the intersection of capital intensity and technical consequence.
- High-capacity electrolysis lines, where stack durability and supply assurance directly affect expansion timing.
- Liquid hydrogen storage and transfer, where fabrication quality and insulation reliability shape operating loss profiles.
- Hydrogen-ready power assets, where conversion pathways must match actual fuel availability and combustion performance.
- CCUS-linked industrial hubs, where carbon management and hydrogen production increasingly share infrastructure logic.
- 70MPa+ refueling systems, where safety architecture, protocol consistency, and maintenance discipline cannot be treated lightly.
Across these areas, manufacturing market updates reveal a broader pattern. Projects with the strongest outlook are those built around verifiable specifications rather than broad technology narratives.
A useful framework for reading the market
Not every market movement requires an immediate response. It helps to separate short-term noise from signals that materially change project design or investment timing.
Questions worth testing against each update
- Does this update affect asset integrity, safety compliance, or lifetime economics?
- Is the change local to one supplier, or visible across the manufacturing base?
- Will it alter permitting, insurance, or financing assumptions?
- Does it create a sequencing issue between production and downstream infrastructure?
- Can the claim be benchmarked against recognized standards or operational evidence?
This kind of filter is increasingly necessary because the hydrogen market is maturing unevenly. Some assets are scaling quickly, while adjacent systems still face constraints in materials, logistics, or certification capacity.
That unevenness is exactly why manufacturing market updates deserve close attention. They help distinguish between a technology that is available and a project chain that is genuinely executable.
What to watch next
The next wave of manufacturing market updates will likely center on three issues: deeper localization of supply chains, tighter linkage between standards and finance, and stronger competition around high-performance components.
That means the smartest next step is not simply to track pricing. It is to map each hydrogen initiative against technical dependencies, benchmark requirements, and infrastructure interfaces before capital is locked in.
A disciplined review of electrolysis systems, cryogenic logistics, hydrogen-ready power, CCUS alignment, and refueling architecture can reveal where assumptions remain weak. From there, market signals become more useful because they are tied to real project decisions.
In 2026, manufacturing market updates are most valuable when they support structured judgment. The organizations that read them well will not just follow the hydrogen transition. They will shape how it is built.
Related News
- Electricity Price Volatility Is Rewriting Hydrogen Cost ModelsApr 27, 2026Impact of electricity price on hydrogen cost is transforming industrial decarbonization and large-scale electrolysis. Explore LCOH trends, PPA strategies, and resilient hydrogen infrastructure planning.
- Energy Transition Plans Often Fail at the Grid Connection StageApr 27, 2026Sustainable energy and energy transition projects often fail at grid connection. Learn how hydrogen infrastructure, PEM electrolysis, and industrial decarbonization can avoid delays and protect investment value.
- What Is Slowing Industrial Decarbonization Projects in 2026?Apr 27, 2026Industrial decarbonization faces delays in 2026 as hydrogen infrastructure, sustainable energy access, grid limits, safety standards, and project bankability challenge the energy transition.
- How G-HEI benchmarking can reveal PEM electrolyzer reliabilitySep 07, 2026G-HEI PEM electrolyzer benchmarking reliability reveals lifecycle risks, dynamic-duty performance, safety controls, and maintainability for smarter hydrogen investments.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.