
What a Wind-to-Hydrogen Project ROI Calculation Tool Should Include




For finance approvers evaluating strategic hydrogen investments, a wind-to-hydrogen project ROI calculation tool should do far more than estimate payback. It must connect capex, power-price volatility, electrolyzer efficiency, storage and transport costs, policy incentives, and risk-adjusted returns into one decision-ready framework. In large-scale zero-carbon infrastructure, the right model helps decision-makers compare scenarios with confidence and approve projects that are technically sound, bankable, and aligned with long-term energy transition goals.
A weak model makes almost any hydrogen project look attractive on paper. A useful one does the opposite: it exposes where project economics are fragile, which assumptions truly drive returns, and how sensitive value is to changes in electricity, utilization, policy support, and delivered hydrogen pricing.
That distinction matters more in wind-to-hydrogen than in many other energy investments. These projects combine renewable generation economics, electrolysis performance, balance-of-plant reliability, storage and logistics constraints, and policy dependency into one capital-intensive asset. For a finance approver, the question is not whether green hydrogen has strategic relevance. It is whether a specific project, under a specific operating model, can deliver acceptable returns within an acceptable risk envelope.
Why a simple payback model is not enough
Many internal screening tools still reduce project viability to a small set of inputs: total capex, annual hydrogen output, assumed sale price, and a simple payback period. That may be enough for an early-stage discussion, but it is not enough for an approval memo.
Wind-to-hydrogen economics are highly path-dependent. A project tied to behind-the-meter wind behaves differently from one using a grid-connected hybrid power strategy. A merchant hydrogen model carries very different revenue risk from a captive industrial offtake structure. Electrolyzer utilization can improve economics in one configuration and destroy them in another if it depends on expensive supplemental electricity.
A credible wind-to-hydrogen project ROI calculation tool therefore has to move beyond a single headline metric. Finance teams should expect it to calculate, at minimum, NPV, IRR, discounted payback, DSCR where project finance is relevant, LCOH, and scenario-based downside cases. More importantly, it should show how those outputs are produced.
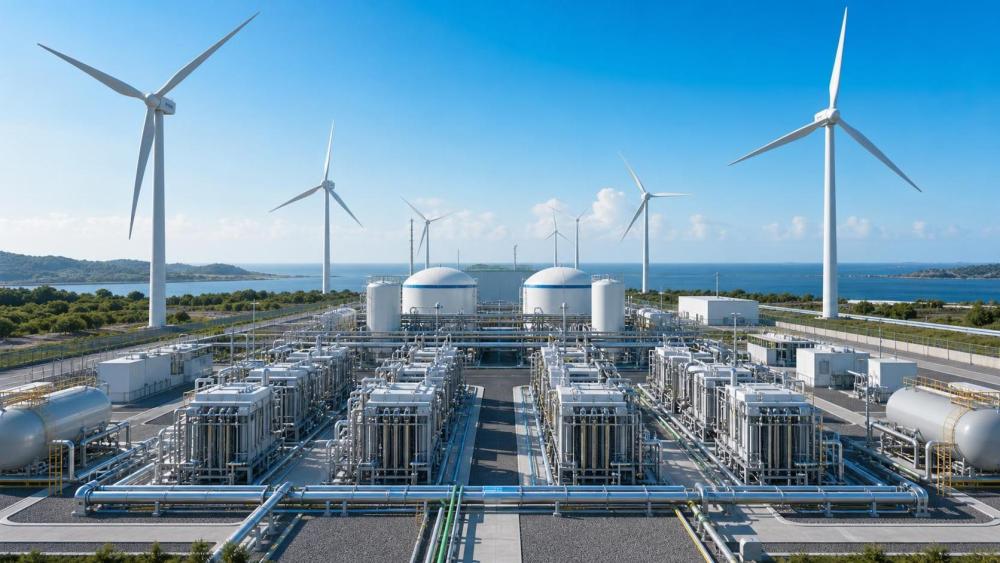
Capex must be broken down at asset level, not treated as one number
The first warning sign in any hydrogen ROI model is a single capex line item. Wind-to-hydrogen projects are too complex for that.
A serious tool should separate at least the following cost categories:
- Wind generation assets or contracted renewable supply costs
- Electrolyzer system cost, separated by stack and balance of plant where possible
- Power conversion and grid interconnection
- Water treatment and supply systems
- Compression, drying, purification, and metering
- Hydrogen storage assets, whether gaseous, liquid, or linepack-related
- Transport infrastructure, if hydrogen is not consumed on site
- Civil works, EPC, commissioning, owner’s costs, and contingency
- Permitting, compliance, insurance during construction, and financing fees
This level of detail is not an accounting preference; it is essential to decision quality. Different capex buckets depreciate differently, carry different replacement cycles, and expose the project to different procurement risks. Stack replacement, for example, is not the same economic issue as vessel integrity management or export compression capacity. A model that blends them together conceals lifecycle cost reality.
Electricity economics should be modeled as the core value driver
In most green hydrogen projects, electricity is the dominant production cost driver over the life of the asset. For wind-to-hydrogen, the challenge is that “power cost” is not one variable. It is a structure of variables.
An approval-grade ROI tool should capture:
- Wind resource profile by hour or at least by representative time block
- Expected curtailment
- Capacity factor assumptions and degradation
- Behind-the-meter versus grid-import operating logic
- Market price exposure for supplemental electricity
- Transmission charges, wheeling, balancing, and ancillary costs where relevant
- Correlation between wind generation and electrolyzer utilization
This is where many optimistic business cases fail. They assume the electrolyzer can run at an economically attractive utilization rate while also using low-cost renewable electricity most of the time. In practice, those two goals can conflict. Higher utilization may require grid imports during low-wind periods, and those imports can materially raise LCOH and reduce margins unless the offtake price supports it.
Finance approvers should be cautious of models using annual average electricity cost alone. Hourly or sub-hourly dispatch modeling is often what separates a realistic hydrogen business case from an overstated one.
Electrolyzer performance cannot be limited to nameplate efficiency
It is common to see electrolysis assumptions presented through a single efficiency figure, often under idealized conditions. That is not enough for investment approval.
The tool should account for:
- Efficiency at different load factors, not just rated load
- Start-stop behavior and partial-load performance
- Degradation over time
- Stack replacement timing and cost
- Availability and forced outage assumptions
- Water consumption and treatment quality requirements
- Parasitic loads across the full hydrogen production system
For wind-coupled systems, dynamic operation matters. If the wind profile forces frequent load changes, project economics depend not only on nominal efficiency but also on how the system performs under variable input conditions. A tool that ignores operational reality may systematically overstate annual hydrogen output and understate maintenance cost.
That issue has become more important as projects scale. At utility level, small performance gaps translate into large revenue and cash-flow differences over the project life.
Hydrogen output value must reflect delivery condition, not just production volume
Not all kilograms of hydrogen have the same economic value. A model that prices hydrogen solely at plant-gate production volume misses a major part of the commercial picture.
Finance teams should require the tool to distinguish between:
- Hydrogen sold at production pressure versus compressed for transport or refueling
- On-site captive use versus merchant delivery
- Pipeline injection, industrial feedstock supply, mobility use, or power generation use
- Purity requirements and associated processing costs
- Take-or-pay offtake structures versus spot or short-term contract exposure
This matters because downstream conditioning costs can significantly alter project returns. Compression to high pressure, liquefaction, or specialized transport can absorb more value than early-stage project models often acknowledge. For some projects, hydrogen production is not the margin problem; delivery is.
The right tool should therefore model netback revenue, not only gross selling price. For finance approvers, that distinction is critical when comparing an apparently attractive merchant case with a lower-priced but more secure industrial offtake agreement.
Opex should include the costs that sponsors often understate
Operating expenditure in wind-to-hydrogen is often underestimated because developers focus on power and maintenance while underweighting support costs that become material over time.
An approval-ready model should include:
- Routine and major maintenance by asset class
- Stack replacement and refurbishment
- Water procurement and treatment
- Labor, remote operations, and specialist service contracts
- Insurance and regulatory compliance costs
- Spare parts inventory and critical component lead-time risk
- Storage losses, boil-off where applicable, and compression energy
- Land lease, network fees, and site security
It should also handle escalation properly. Maintenance costs, labor rates, and insurance do not move at the same pace. Using one generic inflation assumption for all opex categories may be convenient, but it weakens financial decision-making.
Policy incentives should be modeled transparently and separately
In 2026, many wind-to-hydrogen projects still depend heavily on policy support. That can include production tax credits, capex grants, contracts for difference, renewable energy certificate structures, carbon pricing impacts, or public offtake support. The exact instruments vary by jurisdiction, and some are still evolving.
Because support regimes are jurisdiction-specific and subject to revision, a finance-grade tool should not bury incentives inside a blended revenue number. It should isolate them clearly and allow users to switch them on and off by scenario.
At a minimum, it should show:
- Base-case economics without incentives
- Economics with currently awarded or legally confirmed support
- Economics with expected but not yet secured support
- Expiry dates, compliance conditions, and clawback risks
This separation is essential for approval discipline. A project that only clears return thresholds under speculative policy assumptions is fundamentally different from one that remains viable under an unsubsidized or partially subsidized case.
Financing structure belongs inside the tool, not outside it
Some ROI calculators stop at pre-financing economics. That may be acceptable for technical benchmarking, but not for financial approval. Capital structure affects decision quality.
A proper model should include debt-equity assumptions, cost of capital, drawdown schedules, interest during construction, covenant impacts, repayment profile, and refinancing risk where relevant. It should also test delays in commissioning, because schedule slippage in large infrastructure projects directly affects interest capitalization and revenue commencement.
For large sovereign or utility-scale projects, the tool should also support multi-stage investment logic: pilot phase, first commercial phase, and scale-out phase. Many boards do not approve the full platform at once. They approve exposure in steps. A good model should help finance teams evaluate whether phased deployment improves risk-adjusted returns or merely delays inevitable cost recognition.
Risk analysis should be scenario-based, not cosmetic
Every hydrogen project deck includes sensitivity charts. Many are too shallow to matter. A few percentage points up or down on capex and selling price do not capture the true risk profile.
For wind-to-hydrogen, a meaningful ROI calculation tool should stress-test at least these variables:
- Wind resource underperformance
- Electrolyzer degradation and lower-than-planned availability
- Construction delay and cost overrun
- Grid power price spikes for supplemental electricity
- Lower offtake volumes during ramp-up
- Hydrogen price compression due to competing supply
- Delayed incentive approval or reduced policy support
- Higher transport and storage costs than planned
Monte Carlo capability is useful, but only if the input distributions are defensible. In many board settings, a smaller number of carefully constructed downside scenarios is more decision-useful than a statistically elegant output built on weak assumptions.
What finance approvers need is not mathematical sophistication for its own sake. They need visibility into the break points: at what utilization, delivered power cost, or realized hydrogen price does the project stop meeting hurdle rates?
Comparability across project options is a procurement requirement
One of the most practical reasons to invest in a robust tool is supplier and configuration comparison. Procurement decisions in hydrogen are rarely just about selecting the lowest equipment price. They involve trade-offs across technology, operating flexibility, replacement profile, and bankability.
If different bidders or internal teams submit cases based on different modeling logic, financial comparison becomes unreliable. The ROI tool should standardize assumptions and reveal where differences come from: stack efficiency, degradation rate, EPC scope split, availability guarantees, storage philosophy, or integration design.
This is especially important when comparing PEM and alkaline configurations, integrated renewable packages versus decoupled power sourcing, or on-site consumption versus distributed delivery. A common financial framework prevents procurement from being distorted by inconsistent assumptions hidden inside vendor models.
What finance approvers should challenge before signing off
Before approving a wind-to-hydrogen project, finance decision-makers should ask a few hard questions of the model itself.
- Does the model reflect operational dispatch reality, or only annual averages?
- Are stack replacement and degradation treated explicitly?
- Is hydrogen priced at the actual delivery condition required by the customer?
- Can the project meet minimum return thresholds without unconfirmed incentives?
- Which three assumptions drive most of the valuation?
- How much value depends on utilization that may only be achievable through higher-cost grid imports?
- Are logistics and compliance costs fully included, or parked outside the core model?
If the answers are unclear, the issue is not only modeling quality. It is governance risk. A project of this type should not reach approval based on conceptual optimism or vendor-supplied economics that cannot be independently tested.
The best tool is one that makes uncertainty visible
A wind-to-hydrogen project ROI calculation tool should not be expected to eliminate uncertainty. Its job is to organize uncertainty into a form that supports capital allocation.
For finance approvers, the most valuable models are rarely the ones with the most impressive dashboards. They are the ones that make commercial fragility visible early: where electricity costs dominate, where utilization assumptions are unrealistic, where policy support is carrying too much of the return, or where downstream logistics quietly erode margins.
In a market moving from pilot ambition to industrial-scale execution, that is the standard worth applying. If a tool can show not just the upside case but the economic mechanics, downside resilience, and approval conditions of a wind-to-hydrogen investment, it is doing what finance teams actually need it to do.
Related News
- Electricity Price Volatility Is Rewriting Hydrogen Cost ModelsApr 27, 2026Impact of electricity price on hydrogen cost is transforming industrial decarbonization and large-scale electrolysis. Explore LCOH trends, PPA strategies, and resilient hydrogen infrastructure planning.
- Energy Transition Plans Often Fail at the Grid Connection StageApr 27, 2026Sustainable energy and energy transition projects often fail at grid connection. Learn how hydrogen infrastructure, PEM electrolysis, and industrial decarbonization can avoid delays and protect investment value.
- What Is Slowing Industrial Decarbonization Projects in 2026?Apr 27, 2026Industrial decarbonization faces delays in 2026 as hydrogen infrastructure, sustainable energy access, grid limits, safety standards, and project bankability challenge the energy transition.
- How G-HEI benchmarking can reveal PEM electrolyzer reliabilitySep 07, 2026G-HEI PEM electrolyzer benchmarking reliability reveals lifecycle risks, dynamic-duty performance, safety controls, and maintainability for smarter hydrogen investments.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.