
When does zero-carbon infrastructure justify the higher upfront cost?




Zero-carbon infrastructure earns the right to cost more only when the premium can be traced to durable operating value rather than an abstract sustainability claim. In practice, that value usually comes from a combination of lower exposure to carbon costs, more reliable access to energy or feedstocks, compliance with emerging market rules, and the ability to expand capacity without replacing the first generation of assets.
This distinction matters because the capital gap can be substantial. A renewable-power-connected electrolyser, liquid-hydrogen handling system, carbon capture train, hydrogen-capable turbine, or 70 MPa refuelling station may require more engineering, specialist materials, safety systems, commissioning work, and certification than a conventional alternative. The relevant question is not whether its purchase price is higher. It is whether the conventional option creates a larger and less visible liability over the asset’s operating life.
That assessment must be made at the level of the full system. An electrolyser with strong stack performance can still be a poor investment if electricity sourcing is volatile, water treatment is underspecified, compression capacity becomes a bottleneck, or the expected offtake contract does not support the hydrogen cost. Likewise, a carbon capture project can look attractive on capture-rate assumptions but fail financially if transport, storage access, long-term monitoring, and liability allocation are not secured.
The upfront premium is justified when the baseline is genuinely more expensive over time
Capital expenditure is visible, immediate, and easy to compare. Lifecycle exposure is more difficult to model, especially where regulations, fuel markets, and customer requirements are changing. Yet this is where many zero-carbon infrastructure decisions are won or lost.
A conventional asset may appear cheaper because it excludes costs that will arise later: carbon pricing, emissions-reporting obligations, higher insurance requirements, fuel-supply disruption, constrained export-market access, retrofit downtime, and early retirement. The low initial bid may therefore be a short-duration saving rather than a low-cost solution.
For a higher-cost zero-carbon option to be credible, the business case should quantify at least five categories of value:
- Energy and feedstock cost: electricity, natural gas, hydrogen, CO₂ transport, water, fuel conditioning, and backup supply.
- Carbon and compliance exposure: direct emissions costs, embedded-carbon requirements, product certification, reporting systems, and the risk of future tightening.
- Availability and maintenance: expected operating hours, planned outages, stack replacement intervals, spare-parts strategy, specialist service access, and degradation assumptions.
- Revenue protection or uplift: long-term offtake eligibility, access to low-carbon procurement programs, customer specifications, and the ability to preserve market access.
- Residual flexibility: whether the asset can run on changing fuels, connect to future networks, increase capacity in modules, or be repurposed without major civil reconstruction.
These factors should be compared against a conventional reference case that includes realistic future costs. A model that assumes static fuel prices, no carbon constraint, and unlimited grid capacity will systematically favor legacy infrastructure—even in sectors where those assumptions are no longer operationally safe.
Hydrogen projects justify premium capital only when the whole chain is bankable
Hydrogen is often discussed as if production technology determines the investment outcome. It does not. For large-scale projects, the economics are usually governed by the relationship between electricity price, utilisation rate, delivered hydrogen specification, compression or liquefaction requirements, and contracted demand.
PEM electrolysers can offer operating flexibility and rapid response characteristics that are useful where renewable generation varies or grid-balancing value exists. Alkaline systems remain relevant where sustained operation and lower equipment cost are priorities. Neither technology is inherently the better purchase without understanding the operating profile. A plant designed for high utilisation on stable low-cost electricity faces a different decision from one expected to follow intermittent renewable generation.
The higher initial cost of electrolytic hydrogen can be justified where it replaces an emissions-intensive feedstock in ammonia, refining, methanol, steel, chemicals, or mobility applications; where customers pay for certified low-carbon product; or where local energy security has strategic value. It is much harder to justify where hydrogen is produced without a contracted buyer, where power costs are uncertain, or where the project assumes future pipeline access that has not been financed or permitted.
Particular care is needed with “hydrogen-ready” claims. A turbine, pipeline, storage system, or industrial burner may be technically capable of accepting some hydrogen blend, but that is not the same as being ready for high-percentage or 100% hydrogen service. Materials compatibility, seal performance, combustion dynamics, NOx control, metering, pressure management, and local approval requirements all change as hydrogen content rises. The procurement specification should state the required fuel composition, pressure range, ramping duty, emissions performance, warranty boundaries, and conversion scope. Anything less leaves the buyer funding an option that may not be executable.
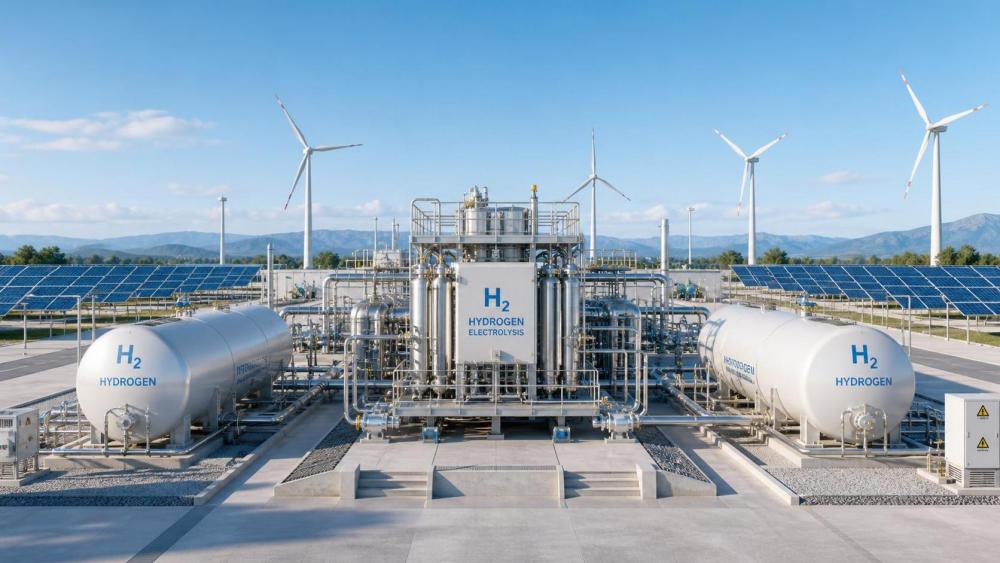
Safety and material integrity are not optional premiums
In zero-carbon infrastructure, some apparent “extras” are actually conditions of insurability, permitting, and reliable operation. This is especially true in high-pressure and cryogenic hydrogen systems.
Hydrogen’s small molecular size, wide flammability range, and potential effects on certain materials require disciplined engineering. At pressures associated with heavy-duty refuelling and tube-trailer systems, component selection, fatigue performance, leak detection, venting, hazardous-area classification, emergency shutdown logic, and inspection access are integral to the design. Reducing capital cost by simplifying these elements may only move the cost into construction change orders, commissioning delay, insurance exclusions, or future downtime.
For refuelling infrastructure, ISO 19880-1 addresses general safety requirements for gaseous hydrogen fuelling stations, while SAE J2601 provides fuelling protocols for light-duty hydrogen vehicles. These standards do not eliminate the need for project-specific engineering, but they provide an important reference point for supplier qualification and acceptance planning. High-pressure piping and piping systems may also need to be assessed against applicable codes, including ASME B31.12 where relevant to the jurisdiction and scope.
Cryogenic liquid-hydrogen logistics introduce a different set of cost realities. Vacuum-insulated storage, boil-off management, transfer equipment, loading cycles, and operational training determine whether a theoretically efficient supply route works in daily service. A lower-cost vessel package can become expensive if insulation performance, thermal cycling tolerance, instrumentation reliability, or maintenance support are weak. Since liquefaction itself is energy-intensive, every avoidable loss in storage and distribution weakens the original emissions and cost case.
The practical rule is straightforward: pay more for engineered risk reduction when it reduces a defined failure mode with material consequences. Do not pay more merely because a system is described as “advanced,” “green,” or “future-proof.”
CCUS needs a liability and transport answer before capture equipment is selected
Carbon capture, utilisation, and storage can be indispensable in sectors where process emissions are difficult to eliminate, including cement, chemicals, refining, and some hydrogen production pathways. However, capture equipment is only one part of the economic decision.
A project should not treat a high capture-rate figure as proof of value. The meaningful questions are whether the captured stream meets transport and storage specifications, who controls access to pipeline or shipping capacity, what happens during transport interruptions, who bears responsibility for storage monitoring, and whether the storage solution has a credible permitting path. Capture also consumes energy, and that energy penalty must be included in both operating cost and net-emissions calculations.
The premium for capture infrastructure is defensible when storage capacity is contracted or otherwise demonstrably available, emissions liabilities are significant, and the underlying industrial asset has a sufficiently long remaining life. It is less defensible when the project relies on an uncommitted storage network, unclear cross-border CO₂ rules, or utilisation routes that cannot absorb the expected volumes over time.
In procurement terms, separating the capture island from CO₂ conditioning, compression, transport interface, and storage obligations may reduce initial bid prices but can create costly interface risk. Contracts should make performance boundaries explicit: inlet-gas composition, capture rate, energy consumption, CO₂ purity, impurity limits, availability, emissions measurement, and remedies for underperformance.
Use a lifecycle model, but do not hide uncertainty inside one number
Net present value and levelised-cost models are necessary, but they can create false confidence when key assumptions are presented as fixed. Zero-carbon infrastructure is particularly sensitive to power price, capacity factor, financing cost, carbon price, utilisation, and construction schedule. A single “base case” should never be the sole basis for approval.
A more useful procurement model tests downside cases explicitly. What happens if renewable electricity is available fewer hours than expected? If electrolyser utilisation falls by 20%? If stack replacement is required earlier than planned? If CO₂ transport is delayed? If hydrogen offtake begins two years later? If a project receives no premium for low-carbon product after its first contract term?
The decisive metric is often not the lowest expected cost but the resilience of the project under plausible adverse conditions. A solution with slightly higher capital expenditure and stronger availability guarantees, broader operating range, proven service capability, or modular expansion may produce a lower risk-adjusted lifecycle cost than a cheaper alternative with narrow operating limits.
Financial models should also distinguish between costs that are controllable and costs that are merely forecast. Equipment price, warranty structure, spare-parts inventory, construction scope, and service commitments can be negotiated. Grid tariffs, power-market volatility, future carbon rules, and hydrogen demand cannot. A sound contract places as much risk as possible with the party capable of managing it, rather than treating uncertainty as a spreadsheet adjustment.
Procurement should test supplier promises against operating evidence
For large infrastructure packages, technology selection cannot rely only on nameplate capacity, reference lists, or headline efficiency. Reference projects should be examined for operating conditions that actually resemble the proposed application. A supplier may have deployed equipment at scale, yet not under the same duty cycle, ambient conditions, hydrogen purity requirement, grid connection regime, or maintenance model.
Due diligence should focus on questions that reveal execution quality:
- What performance is guaranteed at the actual site conditions rather than at nominal test conditions?
- How are degradation, availability, and energy consumption measured and verified?
- Which critical components have single-source dependency or long replacement lead times?
- What certifications, factory acceptance tests, site acceptance tests, and third-party inspections apply?
- Who owns interface engineering among power supply, control systems, compression, storage, civil works, and safety systems?
- What is the supplier’s liability if performance guarantees conflict with changing feedstock or grid conditions?
- Can the equipment be serviced locally, and are trained technicians and strategic spares available throughout the operating period?
Factory acceptance testing is valuable, but it does not prove integrated site performance. The contract should include a commissioning and reliability demonstration period with agreed test methods. For electrolysis and hydrogen handling assets, this should cover not only output but also purity, specific energy consumption, start-stop behavior, safety-system performance, and availability. For turbines and combustion equipment, fuel composition and emissions limits must be tied to tested operating envelopes.
The best projects purchase optionality selectively
Future-readiness has become one of the most misused terms in infrastructure procurement. It can justify sensible design choices, such as allocating space for additional electrolyser trains, oversizing selected cable routes where expansion is likely, or installing control architecture that can accommodate future assets. It can also become a way of funding expensive capabilities that will never be used.
Optionality is worth paying for when there is a credible trigger for its use: a contracted expansion right, a planned industrial demand increase, a known regulatory milestone, or a likely interconnection development. It is not worth paying for when the trigger is only a broad expectation that hydrogen markets will grow.
Modular design can reduce this risk. Instead of committing immediately to maximum capacity, a project can establish shared utilities, safety systems, land preparation, and permitting for expansion while installing the first phase against secured demand. This approach costs more than a minimal first phase, but less than building stranded capacity. It also preserves the ability to benefit from technology improvements and lower equipment costs in later phases.
A higher price is justified only when it buys a better decision, not a better narrative
Zero-carbon infrastructure should be approved when the additional upfront investment produces measurable protection against carbon, fuel, compliance, supply-chain, or asset-obsolescence risk—and when that protection is supported by contracts, engineering evidence, and realistic operating assumptions.
It should not be approved merely because it aligns with a long-term ambition, carries an impressive efficiency claim, or may become valuable if several uncertain market conditions develop simultaneously. The strongest projects are built around verified demand, secure energy inputs, disciplined safety design, credible lifecycle cost scenarios, and enforceable supplier commitments.
That standard may slow early procurement decisions. It also prevents a more expensive outcome: acquiring low-carbon equipment that is technically impressive, politically visible, and commercially stranded.
Related News
- Electricity Price Volatility Is Rewriting Hydrogen Cost ModelsApr 27, 2026Impact of electricity price on hydrogen cost is transforming industrial decarbonization and large-scale electrolysis. Explore LCOH trends, PPA strategies, and resilient hydrogen infrastructure planning.
- Energy Transition Plans Often Fail at the Grid Connection StageApr 27, 2026Sustainable energy and energy transition projects often fail at grid connection. Learn how hydrogen infrastructure, PEM electrolysis, and industrial decarbonization can avoid delays and protect investment value.
- What Is Slowing Industrial Decarbonization Projects in 2026?Apr 27, 2026Industrial decarbonization faces delays in 2026 as hydrogen infrastructure, sustainable energy access, grid limits, safety standards, and project bankability challenge the energy transition.
- How G-HEI benchmarking can reveal PEM electrolyzer reliabilitySep 07, 2026G-HEI PEM electrolyzer benchmarking reliability reveals lifecycle risks, dynamic-duty performance, safety controls, and maintainability for smarter hydrogen investments.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.