
Industry Trends Affecting SOEC Adoption in 2026




In 2026, industry trends are changing the pace and direction of SOEC adoption more quickly than many expected. Solid oxide electrolysis is no longer discussed only as an emerging hydrogen technology. It is now evaluated as part of national energy security, industrial decarbonization, and long-duration infrastructure planning.
That shift matters because SOEC sits at the intersection of power markets, heat integration, hydrogen logistics, and compliance. For organizations tracking large-scale transition pathways, the key question is no longer whether hydrogen will matter, but where SOEC fits within a broader zero-carbon system.
Across the market, industry trends point toward stricter efficiency expectations, stronger material-integrity standards, and higher scrutiny around lifecycle economics. In that environment, decisions about SOEC adoption need to be tied to real operating conditions, not just headline conversion numbers.
Why SOEC is drawing more attention in 2026
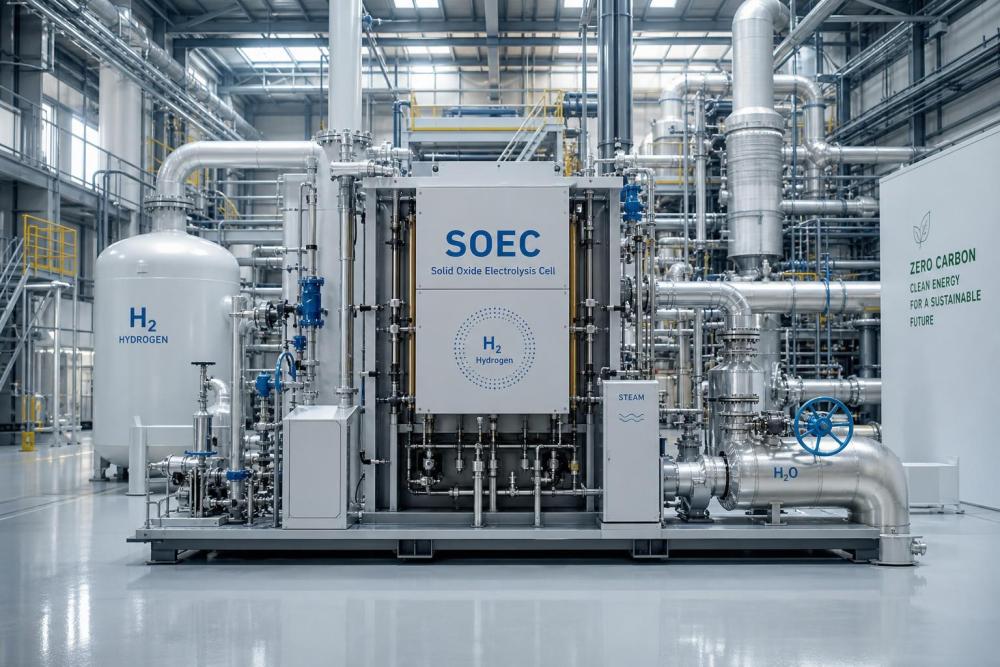
SOEC, or solid oxide electrolysis cell technology, uses high-temperature electrolysis to produce hydrogen. Its main appeal comes from efficiency potential, especially when high-grade heat is already available from industrial or power-generation processes.
This makes SOEC especially relevant in ammonia, refining, e-fuels, steel, chemicals, and integrated utility systems. In these settings, waste heat, steam availability, and continuous operation can improve the business case.
Another reason for growing interest is timing. Many decarbonization roadmaps have moved beyond pilot language. They now require bankable assets, measurable efficiency, and infrastructure compatibility across production, transport, storage, and end use.
That is where the current industry trends become decisive. SOEC is not competing in isolation. It is being judged against PEM, alkaline systems, hydrogen-ready turbines, cryogenic logistics, CCUS pathways, and grid constraints.
The industry trends that are shaping adoption
Several industry trends are influencing whether SOEC moves from promising technology to scaled deployment. Some are technical, while others are financial, regulatory, and geopolitical.
Sovereign decarbonization is becoming infrastructure policy
Hydrogen strategies are no longer limited to climate commitments. They increasingly support energy sovereignty, industrial resilience, and supply-chain independence. That raises demand for electrolysis systems that can support national-scale planning.
In this context, SOEC gains attention where high efficiency can reduce long-term electricity demand. For large economies managing fuel imports and industrial emissions together, that is a strategic consideration, not a marginal one.
Hydrogen infrastructure investment is becoming more selective
Capital is still flowing into hydrogen, but funding standards are harder. Investors and operators now want stronger proof on utilization rates, thermal integration, degradation behavior, and downstream compatibility.
That favors projects that connect production to practical offtake. It also favors reference frameworks like G-HEI, which benchmark assets across the zero-carbon value chain rather than evaluating electrolyzers in isolation.
Efficiency claims are being tested against system reality
One of the strongest industry trends in 2026 is the move from stack-level claims to full-system performance analysis. For SOEC, that means heat source quality, steam purity, startup cycling, integration losses, and balance-of-plant design matter as much as cell chemistry.
A system that looks efficient on paper may struggle if the thermal profile is unstable. That is why practical adoption increasingly depends on site-specific engineering rather than generic technology comparisons.
Safety and material-integrity standards are rising
As hydrogen assets scale, compliance expectations are expanding. Material brittleness, thermal stress, sealing durability, and hydrogen handling interfaces are under closer review.
G-HEI’s relevance is clear here. Its focus on benchmarking against frameworks such as ISO 19880, ASME B31.12, and SAE J2601 reflects a broader market reality: adoption depends on technical credibility across the full asset lifecycle.
Where SOEC creates the most business value
SOEC is not the best fit for every hydrogen project. Its value is strongest where the surrounding process can unlock its thermal advantage and where operating profiles support higher utilization.
These use cases show why current industry trends cannot be read through cost alone. System architecture, infrastructure readiness, and risk tolerance are equally important when evaluating long-term value.
What decision quality looks like in practice
A better SOEC decision usually starts with a better boundary definition. Instead of asking whether SOEC is more efficient in general, the more useful question is whether it is more effective in a given operating environment.
In practice, five checks tend to separate robust projects from weak ones:
- Confirm whether high-temperature heat is available, stable, and economically usable.
- Model degradation under realistic cycling rather than ideal laboratory conditions.
- Evaluate hydrogen output against storage, transport, and end-use interfaces.
- Test compliance pathways early, especially for pressure, piping, and fueling links.
- Compare SOEC with PEM and alkaline options at full-plant level, not unit level.
This is also why benchmarking platforms matter. G-HEI’s cross-sector structure is useful because SOEC performance does not exist apart from cryogenic logistics, turbine readiness, CCUS interfaces, and fueling standards.
When those links are ignored, projects often overestimate efficiency gains and underestimate integration risk. When those links are measured early, adoption decisions become much clearer.
Signals that deserve closer monitoring this year
The most important industry trends for the rest of 2026 will likely come from execution data rather than policy headlines. Several signals deserve close attention.
Commercial proof beyond pilot announcements
Look for projects reporting uptime, degradation, and delivered hydrogen cost under real operating loads. Announced capacity matters less than repeatable performance.
Standard alignment across the hydrogen chain
Stronger links between production standards and downstream infrastructure standards will accelerate confidence. Fragmented compliance remains a drag on scale.
Integration with power and thermal assets
SOEC adoption will rise fastest where it is paired with existing heat sources, hydrogen-ready generation, or industrial process redesign. Standalone deployment will stay harder to justify.
Supply-chain maturity for critical materials
Material integrity is not only a technical issue. It is a procurement and resilience issue. The next wave of industry trends will reward technologies supported by durable component ecosystems.
A practical way to move forward
SOEC deserves attention in 2026 not because it is universally superior, but because current industry trends make its advantages more relevant in the right settings. The strongest opportunities appear where energy efficiency, thermal integration, and sovereign infrastructure planning now overlap.
The most useful next step is to build a structured comparison around site conditions, compliance exposure, heat availability, infrastructure links, and long-term hydrogen demand. That kind of assessment creates a clearer basis for technology choice than market noise alone.
As the hydrogen economy matures, decisions will increasingly favor systems that can prove performance across the full chain. Tracking industry trends through that wider lens is the most reliable way to judge whether SOEC should remain under review, move into pilot scope, or advance toward deployment.
Related News
- DOE Expands SOEC Federal Procurement AccessJul 10, 2026DOE expands SOEC federal procurement access, adding qualified Chinese manufacturers subject to NETL durability validation. Learn what this means for bids, compliance, and market entry.
- DOE SOEC Guide Adds Carbon Footprint Filing RuleJul 08, 2026DOE SOEC Guide update: new carbon footprint filing rules now require ISO 14067 declarations for nickel-based components. Learn how this affects bidding, exports, compliance, and delivery readiness.
- DOE Reviews Export Controls for SOEC Ni-YSZ MembranesJul 07, 2026DOE Reviews Export Controls for SOEC Ni-YSZ Membranes: learn how this policy review may affect sourcing, compliance, exports, and project delivery before the August 5, 2026 comment deadline.
- IAHE Tightens SOEC Export Filing for Ni-YSZ MembranesJul 06, 2026IAHE Tightens SOEC Export Filing for Ni-YSZ Membranes: learn how the 60-day advance filing rule affects SOEC exports, compliance planning, delivery timelines, and global project execution.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.