
Sustainable Energy Investment Risks and Return Signals




Why is sustainable energy investment being judged more carefully now?
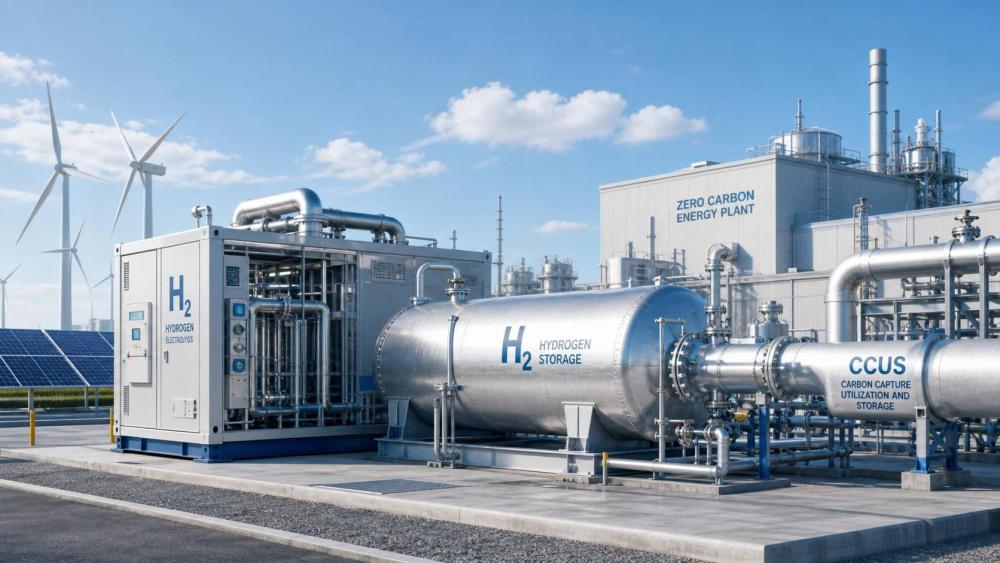
Sustainable energy investment is no longer evaluated on climate ambition alone.
Capital approval now depends on whether projects can prove durability, compliance strength, and reliable return logic across long operating cycles.
That shift is especially visible in hydrogen, CCUS, and zero-carbon infrastructure.
These sectors promise structural growth, but they also introduce unfamiliar engineering, transport, and safety exposures.
In practical terms, sustainable energy investment now sits between two pressures.
One is policy momentum toward decarbonization.
The other is a stricter demand for evidence that assets will perform under real operating conditions.
This is where technical benchmarking matters.
Platforms such as G-HEI have become useful because they connect strategic energy themes with asset-level proof.
Instead of treating hydrogen infrastructure as a broad growth story, they compare electrolyzers, cryogenic vessels, gas turbines, refueling systems, and CCUS assets against standards that influence insurability and uptime.
That changes the conversation from optimism to measurable investment quality.
What counts as a credible return signal in sustainable energy investment?
A credible return signal usually combines market demand, technical readiness, and regulatory fit.
If one of those pieces is weak, the headline opportunity can become misleading.
For example, a hydrogen project may look attractive because subsidy support is strong.
Yet the investment case weakens if electrolyzer efficiency degrades too quickly, if storage losses are underestimated, or if logistics assets are not built to recognized codes.
More credible signals tend to include the following:
- Long-term offtake structures with creditworthy counterparties.
- Documented alignment with standards such as ISO 19880, ASME B31.12, and SAE J2601.
- Clear replacement and maintenance assumptions for high-stress components.
- Evidence that supply chains for membranes, catalysts, alloys, or insulation systems are stable.
- Revenue sensitivity models that test energy price volatility and utilization swings.
In other words, sustainable energy investment looks stronger when return assumptions are supported by engineering facts.
A project with lower headline yield can still be superior if asset integrity is much more defensible.
Where do hidden risks usually appear first?
They often appear where financial models abstract away physical complexity.
Hydrogen systems are a good example because performance depends on materials behavior, pressure management, thermal losses, and safety compliance.
A project can appear bankable on paper while carrying weak assumptions on embrittlement, boil-off, refueling throughput, or compressor maintenance.
The same pattern shows up in CCUS infrastructure.
Capture efficiency may look satisfactory, but transport and storage liabilities can distort lifecycle economics if monitoring obligations are underestimated.
A useful way to screen sustainable energy investment is to ask where the first non-obvious failure could happen.
This kind of screening creates a better approval discipline than relying on generic growth forecasts.
How should hydrogen and zero-carbon assets be compared when choices look similar?
The difficult part is that many options look equivalent at summary level.
Two projects may both claim strong decarbonization impact and policy support.
The gap usually appears in asset quality, integration burden, and standardization depth.
Take PEM and alkaline electrolysis.
PEM can offer responsiveness advantages for variable renewable input, while alkaline systems may present different cost and maturity profiles.
That does not make one universally better.
It means the better sustainable energy investment depends on load pattern, power sourcing, water quality, maintenance capability, and output requirements.
A similar comparison applies to cryogenic logistics versus compressed gas systems, or hydrogen-ready turbine upgrades versus full equipment replacement.
More grounded comparisons usually examine:
- Expected operating profile, not just nameplate capability.
- Material integrity under pressure, temperature, and cycling stress.
- Retrofit complexity across transport, storage, and downstream use.
- Auditability of performance data from comparable installations.
G-HEI is relevant in this context because benchmarking across the five zero-carbon pillars helps normalize these comparisons.
That makes sustainable energy investment decisions less dependent on vendor narrative and more dependent on verifiable technical posture.
What timelines and cost assumptions deserve the most scrutiny?
Schedule risk in sustainable energy investment often hides inside commissioning and compliance phases.
Large assets can reach mechanical completion while still facing delays in certification, integration testing, or transport readiness.
This matters because delayed revenue starts can materially weaken project IRR.
Cost scrutiny should also go beyond equipment price.
More useful questions include whether spares are regionally available, whether specialized technicians are required, and whether upgrades will be needed to maintain future compliance.
In hydrogen transport and refueling, balance-of-plant costs can become more significant than expected.
In CCUS, monitoring and long-tail stewardship can reshape the economics long after the initial build.
A disciplined review usually checks three time horizons:
- Near term: permitting, engineering lead times, and supplier concentration.
- Mid term: ramp-up stability, maintenance intervals, and utilization reality.
- Long term: retrofit needs, regulation changes, and asset end-of-life obligations.
When these are modeled clearly, sustainable energy investment becomes easier to defend through approval cycles.
What is a practical way to approve sustainable energy investment without relying on optimism?
A practical approach is to treat each project as a layered risk case.
The first layer is market logic.
The second is engineering integrity.
The third is compliance durability over the full asset life.
That structure is more useful than a single blended return estimate.
Before approval, it helps to assemble a short evidence pack.
- A standards map showing which codes govern each major subsystem.
- A degradation and replacement schedule for critical components.
- Scenario tests for energy prices, utilization, and downtime.
- A benchmark comparison against technically similar assets.
- A record of unresolved assumptions that still affect value.
This is where specialist repositories such as G-HEI can add value without turning the process into a product pitch.
They help anchor sustainable energy investment in measurable performance, sovereign-grade infrastructure logic, and cross-border technical standards.
The broader takeaway is straightforward.
Sustainable energy investment is becoming more selective, not less attractive.
Projects tied to hydrogen, cryogenic logistics, hydrogen-ready power, high-pressure refueling, and CCUS can justify long-term capital.
They simply need stronger proof on asset security, standards alignment, and return resilience.
The next step is to define the decision criteria before reviewing project narratives.
Compare technical benchmarks, stress-test lifecycle assumptions, and check whether projected returns survive realistic operating conditions.
That process leads to better capital selection and fewer surprises after approval.
Related News
- DOE Expands SOEC Federal Procurement AccessJul 10, 2026DOE expands SOEC federal procurement access, adding qualified Chinese manufacturers subject to NETL durability validation. Learn what this means for bids, compliance, and market entry.
- DOE SOEC Guide Adds Carbon Footprint Filing RuleJul 08, 2026DOE SOEC Guide update: new carbon footprint filing rules now require ISO 14067 declarations for nickel-based components. Learn how this affects bidding, exports, compliance, and delivery readiness.
- DOE Reviews Export Controls for SOEC Ni-YSZ MembranesJul 07, 2026DOE Reviews Export Controls for SOEC Ni-YSZ Membranes: learn how this policy review may affect sourcing, compliance, exports, and project delivery before the August 5, 2026 comment deadline.
- IAHE Tightens SOEC Export Filing for Ni-YSZ MembranesJul 06, 2026IAHE Tightens SOEC Export Filing for Ni-YSZ Membranes: learn how the 60-day advance filing rule affects SOEC exports, compliance planning, delivery timelines, and global project execution.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Aris Aero
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.