
Industrial Hydrogen for Green Steel: Can Supply Stay Stable at Scale?




As green steel projects move from pilot lines to industrial-scale deployment, the reliability of industrial hydrogen for green steel has become a board-level concern. Stable supply is no longer just a technical issue—it shapes CAPEX risk, plant utilization, cross-border logistics, and long-term competitiveness. For decision-makers, the key question is clear: can hydrogen infrastructure scale fast enough to support continuous, sovereign-grade steel decarbonization?
The short answer is yes—but not everywhere, not under all contract structures, and not without redesigning how hydrogen is produced, transported, stored, and governed. For enterprise leaders, the real issue is not whether hydrogen can technically replace carbon-intensive reductants in steelmaking. It is whether supply can remain continuous, bankable, standards-compliant, and cost-disciplined at the volumes required by direct reduced iron (DRI), hot briquetted iron (HBI), and future integrated green steel platforms.
User search intent behind industrial hydrogen for green steel is highly practical. Decision-makers are not looking for a basic definition of green hydrogen or a broad decarbonization narrative. They want to know whether hydrogen supply can remain stable at industrial scale, what can disrupt that stability, how to evaluate project readiness, and what commercial and infrastructure models best reduce operational and investment risk.
That means the most useful discussion is not generic sustainability messaging. It is a grounded assessment of supply security, load matching, storage buffers, offtake structures, logistics constraints, regulatory compliance, and the operational implications for steel assets that cannot tolerate prolonged interruption. In other words, this is a reliability question before it is a branding question.
Can industrial hydrogen for green steel stay stable at scale? The executive answer
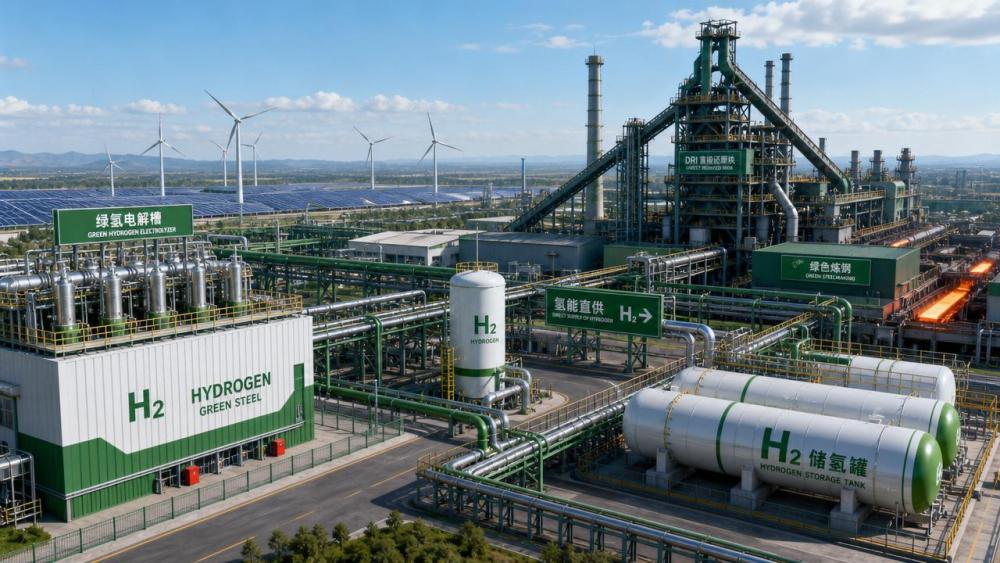
Industrial hydrogen for green steel can stay stable at scale, but only when supply architecture is designed around steel plant realities rather than hydrogen market optimism. A steelmaking complex needs high-volume, high-purity, near-continuous reductant supply. If hydrogen availability fluctuates with power volatility, pipeline bottlenecks, electrolyzer downtime, or delayed imports, plant economics can deteriorate rapidly.
For business leaders, the decisive insight is this: hydrogen stability is not a single-variable problem. It is the outcome of five linked systems working together—power procurement, electrolysis performance, storage capacity, transport infrastructure, and contractual governance. Weakness in any one of these can undermine the full value chain.
In practical terms, supply can be considered stable only when the hydrogen platform can absorb renewable intermittency, equipment maintenance, seasonal imbalances, and logistics shocks without materially reducing DRI output or pushing delivered hydrogen cost outside the project’s modeled range. That is a much higher standard than proving a pilot can run for selected hours under favorable conditions.
Why supply stability matters more in steel than in many other hydrogen end uses
Green steel has a different risk profile from mobility, blending, or distributed industrial heating. Large steel assets are capital-intensive, throughput-sensitive, and deeply dependent on process continuity. Even short supply disruptions can reduce furnace utilization, affect metallization quality, complicate heat integration, and create downstream delivery issues across rolling, finishing, and customer fulfillment.
Unlike some hydrogen applications that can flex around variable availability, steelmakers usually need reliability windows aligned with core production cycles. If hydrogen is the primary reducing agent in DRI operations, it becomes mission-critical feedstock. That elevates supply assurance from an energy procurement matter to a plant resilience and EBITDA protection issue.
This is why enterprise buyers increasingly assess hydrogen the same way they assess iron ore quality, electricity access, water security, and port capacity. Reliability is strategic. It affects debt structuring, insurance assumptions, customer commitments, emissions claims, and the feasibility of premium green steel contracts with automotive, appliance, and infrastructure buyers.
What actually threatens hydrogen supply stability at industrial scale
The first major risk is power volatility. Most green hydrogen projects rely on renewable electricity, but steel plants do not consume hydrogen on a weather-dependent basis. If electrolyzers are fed by variable wind or solar without sufficient grid balancing, long-duration storage, or firming capacity, hydrogen output can become inconsistent. That mismatch is manageable in a demonstration environment, but dangerous in full industrial operations.
The second risk is electrolyzer availability. Nameplate capacity does not equal delivered annual volume. Degradation, stack replacement cycles, water treatment issues, compressor failures, and balance-of-plant inefficiencies can reduce effective output. Decision-makers should examine guaranteed availability, ramp behavior, maintenance strategy, and redundancy design—not just megawatt announcements.
The third risk is logistics immaturity. Regions without dedicated hydrogen pipelines may depend on trucking, rail, ammonia conversion, methanol pathways, or cryogenic liquid hydrogen. Each option introduces cost, conversion losses, handling constraints, permitting complexity, and exposure to bottlenecks. Imported hydrogen can support scale, but only if unloading, storage, reconversion, and inland delivery infrastructure are synchronized.
The fourth risk is storage underinvestment. Many projects overemphasize production and underbuild buffer capacity. Yet storage is what converts variable production into industrial reliability. Without appropriate compressed gas, liquid, salt cavern, or derivative-based storage strategies, even a well-sited hydrogen plant may fail to support continuous steel demand during outages or renewable shortfalls.
The fifth risk is governance and contracting. A project can be technically sound and still commercially unstable if force majeure clauses are weak, quality specifications are unclear, price pass-through is unmanaged, or curtailment risk is shifted onto the steel buyer. Stable supply depends as much on contract architecture as on equipment design.
How to evaluate whether a hydrogen platform is bankable for green steel operations
Executives should start with one core question: what is the delivered hydrogen availability at the plant gate across the full operating year? This should include seasonal scenarios, maintenance windows, renewable variability, transmission congestion, and transport disruptions. If the supplier presents only nominal annual output, the analysis is incomplete.
Next, assess effective redundancy. Is supply dependent on a single electrolyzer field, single power source, single pipeline route, or single import terminal? Single-point failure is unacceptable for large steel operations. Resilient systems layer multiple power inputs, modular electrolysis blocks, backup compression, diversified transport routes, and strategic storage buffers.
It is also essential to evaluate purity and pressure consistency. DRI processes are sensitive to gas quality. Variations in moisture, oxygen contamination, or pressure can affect reactor performance and downstream process control. Industrial hydrogen for green steel must therefore be assessed against process-specific quality tolerances, not generic merchant hydrogen assumptions.
Buyers should also review standards alignment. Infrastructure benchmarked to frameworks such as ASME B31.12, ISO 19880, and relevant materials-integrity and safety protocols is more likely to perform reliably over time. Compliance does not guarantee low cost, but it reduces technical uncertainty, insurance complexity, and failure risk—critical considerations for sovereign-scale steel decarbonization.
Which supply models are most credible for large-scale green steel
No single model fits every geography. However, some structures are clearly more credible than others for early industrial deployment. The first is co-located production, where large electrolyzers are built near steel assets with dedicated renewable power, grid support, and on-site storage. This model minimizes transport complexity and gives operators greater control, though it requires strong local power economics and water access.
The second is regional hydrogen hub supply. In this model, a steel plant draws from shared infrastructure that may include multi-user electrolysis, pipeline networks, storage caverns, and industrial demand clustering. This can improve utilization and reduce unit cost, especially where public policy supports common-carrier infrastructure. The tradeoff is dependence on broader network development timelines.
The third is import-backed hydrogen or derivative supply for countries lacking low-cost renewable resources. This can be viable where ports, ammonia cracking, liquid hydrogen handling, or synthetic carrier infrastructure are robust. For decision-makers, the central question is not whether imports are possible, but whether import dependence creates geopolitical, maritime, or cost-indexation risks that undermine long-term steel competitiveness.
In many cases, the strongest answer is a hybrid model: on-site base production, regional network balancing, and strategic imported backup. Hybridization increases complexity, but it often produces the resilience profile required for continuous industrial operation.
What board-level leaders should ask before approving green steel hydrogen investments
First, can the project tolerate hydrogen intermittency, or does it require near-baseload supply? The answer affects everything from storage sizing to power procurement to the choice between full hydrogen DRI and transitional process configurations. If the plant has low tolerance for interruption, supply infrastructure must be engineered accordingly from day one.
Second, what is the true delivered cost under stress conditions? Many business cases model average hydrogen cost but not contingency cost. Leaders should request downside scenarios covering low renewable output, grid price spikes, import delays, compressor outages, and lower-than-expected electrolyzer utilization. A project that looks attractive only under best-case assumptions is not investment-grade.
Third, who carries performance risk? If suppliers guarantee volume, purity, and pressure with enforceable remedies, the steel producer’s exposure is reduced. If those guarantees are weak, the steel company effectively becomes the residual risk holder. This should be explicit in investment committee discussions.
Fourth, is the infrastructure expandable? Today’s plant may require one scale of hydrogen, but future expansions, downstream finishing, and customer demand for lower embodied carbon may increase volume needs significantly. Infrastructure should be assessed not only for current feasibility, but for pathway scalability over ten to twenty years.
How stable hydrogen supply becomes a competitive advantage, not just a compliance tool
Reliable industrial hydrogen for green steel does more than reduce emissions. It supports commercial differentiation. Automotive OEMs, construction buyers, appliance manufacturers, and public procurement agencies increasingly value supply-backed low-carbon steel, not merely announced decarbonization plans. Producers with credible hydrogen security can offer firmer delivery commitments and more defensible embedded carbon claims.
Supply stability also improves financing credibility. Lenders and equity partners are more likely to support projects where hydrogen is secured through diversified infrastructure, robust standards compliance, and transparent risk allocation. In this sense, hydrogen reliability lowers more than operating risk—it can lower capital friction.
At the national level, stable hydrogen-backed steel production strengthens industrial sovereignty. Countries that can secure domestic or allied hydrogen supply reduce exposure to carbon border adjustments, imported fossil volatility, and strategic dependence on external reductant pathways. For policymakers and major industrial groups alike, this is becoming a competitiveness issue as much as a climate issue.
What a realistic decision framework looks like in 2026
In 2026, the market is beyond concept-stage enthusiasm but not yet fully mature. That means leaders should avoid two extremes: assuming hydrogen scale-up is easy, or assuming instability makes green steel premature. The right approach is disciplined readiness assessment.
A practical decision framework includes six checkpoints: firm power access, validated electrolyzer performance, adequate storage autonomy, compliant transport infrastructure, strong offtake and supply contracts, and phased expansion logic. If even two of these are weak, the probability of operational underperformance rises materially.
Decision-makers should also benchmark assets and partners on technical integrity, not marketing language. Stack chemistry, vessel design, compression reliability, cryogenic handling capability, pipeline standards, and control-system resilience all influence supply continuity. Industrial-scale decarbonization will favor organizations that can distinguish bankable infrastructure from aspirational announcements.
The central lesson is straightforward. Hydrogen can support large-scale green steel, but only where the ecosystem is engineered for continuity. Supply stability is created through system design, not assumed through capacity headlines.
Conclusion: the winners will treat hydrogen stability as core industrial infrastructure
So, can supply stay stable at scale? Yes—when industrial hydrogen for green steel is approached as critical infrastructure rather than a standalone fuel purchase. Stable supply depends on integrated planning across power, production, storage, transport, standards, and contractual risk allocation.
For enterprise decision-makers, the most important takeaway is that hydrogen reliability should be evaluated with the same rigor as any strategic industrial input. The projects most likely to succeed will not be those with the loudest green claims, but those with the strongest redundancy, best infrastructure logic, clearest governance, and most credible pathway to continuous operation.
In the coming cycle of green steel investment, supply stability will separate symbolic decarbonization from scalable industrial transformation. Leaders who assess hydrogen through that lens will be better positioned to protect returns, secure market trust, and build sovereign-grade competitiveness in the low-carbon metals economy.
Related News
- When does a hydrogen steelmaking retrofit make operational sense?Sep 06, 2026Hydrogen steelmaking retrofit: discover the operational conditions, gas-network upgrades, supply strategy, safety controls, and economics needed for a practical, production-ready transition.
- How Hydrogen Ignition Control Reduces Flashback Risk in Direct BurnersAug 13, 2026Hydrogen ignition control helps reduce flashback risk in direct burners by improving timing, mixing, and flame stability—keeping hydrogen combustion safer, cleaner, and more reliable.
- Industrial Hydrogen Solutions for Refineries: Cost Priorities and Retrofit OptionsJul 13, 2026Industrial hydrogen solutions for refineries: compare cost priorities, retrofit paths, and low-carbon options to improve resilience, compliance, and long-term refinery value.
- When to Hire Refinery Decarbonization Consultants for Scope, Cost, and ComplianceJul 12, 2026Refinery decarbonization consultants help buyers define scope, control retrofit costs, and improve compliance readiness. Learn the best time to hire for stronger refinery project decisions.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Hideo Torque
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.