
Utility-Scale Power Transition Projects: Key Cost Drivers in 2026




Boardrooms Are Treating Utility-Scale Power Transition Projects as Cost Architecture Decisions
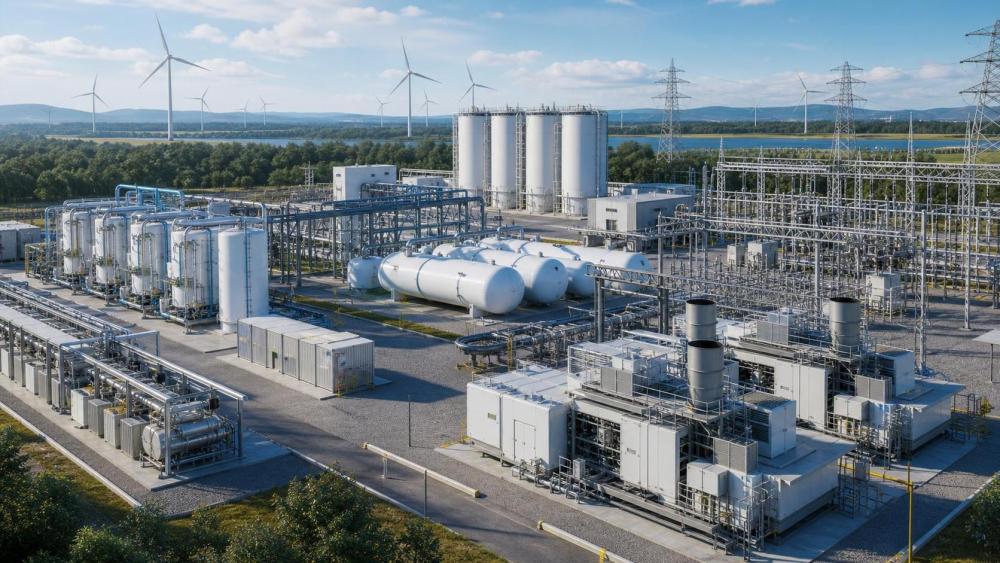
In 2026, utility-scale power transition projects are no longer framed as distant decarbonization pledges. They are being tested as capital-heavy infrastructure choices with measurable balance-sheet consequences.
That shift matters because budgets are no longer driven by equipment price alone. Project value now depends on transport readiness, standards compliance, operating flexibility, and long-horizon asset durability.
Across the broader energy and industrial landscape, utility-scale power transition projects increasingly sit at the intersection of hydrogen production, grid stability, fuel logistics, and carbon management.
The practical question is changing. Instead of asking whether to transition, decision frameworks now ask which cost drivers determine bankability, risk exposure, and residual asset value.
This is where technical benchmarking has become financially relevant. Reference platforms such as G-HEI are gaining weight because capital approval now depends on verified performance, integrity standards, and cross-border comparability.
For utility-scale power transition projects, the strongest cost signals in 2026 are emerging from integrated systems, not isolated components. That changes how budgets should be read from the start.
The Cost Baseline Is Moving Up, but for More Specific Reasons
Recent market movement shows a clear pattern. Front-end estimates are rising, yet the increase is not simply inflation or commodity volatility.
More often, costs are climbing because utility-scale power transition projects are being designed with fewer assumptions and tighter performance guarantees.
Hydrogen-ready generation, large-scale electrolysis, cryogenic storage, and CCUS interfaces all demand higher specification discipline than legacy thermal assets.
This also means early budgets are absorbing engineering realities that were previously deferred. Material selection, pressure management, boil-off control, and pipeline compatibility are entering the model sooner.
The result is a more honest cost curve. It looks steeper upfront, but it can reduce later surprises tied to retrofits, downtime, and compliance corrections.
The strongest upward pressures are now coming from five areas
- Electrolyser system balance-of-plant, especially power conditioning, water treatment, and thermal management.
- Hydrogen transport and storage design, including vacuum-insulated vessels and compression requirements.
- Materials and metallurgy for embrittlement resistance in piping, valves, and turbine-adjacent systems.
- Safety and certification pathways aligned with ISO 19880, ASME B31.12, and related integrity standards.
- Grid integration and dispatch flexibility, especially where renewable intermittency shapes electrolyser utilization.
These are not fringe technicalities. In many utility-scale power transition projects, they now define the difference between a headline budget and a financeable one.
Why Hydrogen-Ready Design Is Becoming a Primary Cost Driver
One of the clearest signals in 2026 is that hydrogen readiness is no longer treated as an optional future upgrade. It is being priced into asset strategy from day one.
That has several implications. Turbine modifications, combustion control systems, blending infrastructure, and compatible storage all push capital intensity above conventional gas-based designs.
Yet the cost logic is not purely defensive. Hydrogen-ready utility-scale power transition projects can preserve long-term dispatch value in markets where carbon pricing and fuel regulation are tightening.
This is why technical detail matters to capital review. A low-cost baseline can look attractive until future conversion costs, outage windows, and permitting revisions are priced realistically.
G-HEI’s relevance in this context comes from its focus on benchmarkable components across the zero-carbon chain. It connects electrolysis output quality, storage integrity, and power conversion readiness into one evaluable picture.
Where hydrogen-readiness changes cost assumptions
Electrolysis Costs Now Depend More on Utilization Than Nameplate Size
A few years ago, many cost discussions centered on stack price per kilowatt. That metric still matters, but it no longer explains enough.
In utility-scale power transition projects, electrolyser economics are now being judged through operating profile, maintenance intervals, purity tolerance, and integration with intermittent power.
PEM systems often command a premium because of dynamic response and compactness. ALK systems can offer cost advantages, but site conditions and load variability shape the real outcome.
What matters more is whether the asset runs in a way that protects stack life while keeping hydrogen output commercially usable.
This is one reason utility-scale power transition projects are leaning harder on technical repositories with benchmark depth. Performance claims now need to be translated into lifecycle cost confidence.
From a budgeting perspective, low utilization is especially dangerous. It inflates hydrogen cost, stretches payback, and can undermine the logic of adjacent storage and transport investments.
Logistics and Compliance Are Moving from Secondary Costs to Core Budget Lines
Another visible change is that logistics are no longer treated as downstream operational details. In many utility-scale power transition projects, they are shaping the investment case early.
Cryogenic liquid hydrogen logistics, compression stations, refueling interfaces, and storage turnover assumptions can alter total project economics more than expected.
The same applies to compliance. Certification work once viewed as administrative now affects schedule, insurance, vendor selection, and financing terms.
That makes standards literacy a cost discipline, not just an engineering concern. ISO 19880, ASME B31.12, and SAE J2601 increasingly influence procurement filters and contingency levels.
Projects that align late often spend more on redesign, retesting, and interface corrections. Projects that align early usually carry a higher development cost, but a cleaner execution path.
The pattern showing up across markets
- More budget is being moved into pre-FEED and detailed engineering.
- Vendor qualification is taking longer because material and safety proofs are deeper.
- Transport assumptions are being stress-tested against real throughput and storage losses.
- Insurance and financing teams are asking for clearer integrity evidence.
For utility-scale power transition projects, these shifts usually increase early spending but reduce the chance of a structurally underpriced asset.
The Bigger Financial Risk May Be Fragmented System Design
A common mistake is to treat generation, hydrogen production, transport, and carbon management as separate budget silos. That approach rarely survives execution cleanly.
Utility-scale power transition projects are increasingly punished by interface failures rather than single-component defects. Mismatched pressure ranges, purity gaps, or dispatch assumptions can cascade into expensive redesign.
This is particularly relevant where hydrogen-ready turbines, CCUS assets, and electrolysis systems must operate inside one commercial envelope.
The more integrated the project, the more valuable cross-domain benchmarking becomes. G-HEI reflects this broader market need by comparing asset classes against consistent safety and performance frameworks.
In practical terms, utility-scale power transition projects are now being judged on whether the whole chain works at sovereign-scale reliability, not whether each subsystem looks credible on paper.
Where to Focus the Next Round of Cost Review
The strongest response is not blanket cost cutting. It is sharper discrimination between price, lifecycle burden, and strategic optionality.
For utility-scale power transition projects under review in 2026, several checkpoints deserve more attention than headline EPC numbers.
- Test whether utilization assumptions for electrolysis still hold under realistic renewable intermittency.
- Map standards compliance costs before locking vendor scope, not after technical selection.
- Model storage and logistics losses with operational detail, including boil-off and compression energy.
- Review whether hydrogen-ready design reduces future retrofit exposure enough to justify present capex.
- Check whether system interfaces have been budgeted, especially across generation, transport, and CCUS.
The projects that look strongest now are not always the cheapest. They are the ones with fewer invisible assumptions and clearer pathways to dependable operation.
That is likely to remain true as utility-scale power transition projects move deeper into deployment. The next step is to compare technical benchmarks, standards exposure, and logistics realism before final capital commitments are locked.
Related News
- When Does a Hydrogen-Ready Gas Turbine Pay Off?Apr 27, 2026Hydrogen-ready gas turbine economics explained: evaluate industrial decarbonization, hydrogen blending, hydrogen infrastructure, and utility-scale power ROI to see when future-proof flexibility truly pays off.
- Why Is Hydrogen Infrastructure Slowing the Energy Transition?Sep 07, 2026Why is energy transition slowing in hydrogen infrastructure? Explore the transport, storage, standards, cost, and investment barriers shaping scalable hydrogen projects.
- How Hydrogen Ready Gas Turbines Balance Low NOx Emissions With Fuel FlexibilityJul 31, 2026Hydrogen ready gas turbines low NOx performance explained: learn how combustor design, controls, and retrofit pathways balance emissions, fuel flexibility, and bankable project value.
- Utility-Scale Hydrogen Power Cost: What Drives CAPEX and OPEX in 2026Jul 11, 2026Utility-scale hydrogen power cost in 2026 depends on more than equipment price. Discover the real CAPEX and OPEX drivers, key risk factors, and smarter ways to evaluate project value.
Related News
- 00
0000-00
Hydrogen Energy Storage for Data Centers Gets Costly Fast - 00
0000-00
When 99.999% Hydrogen Purity Still Is Not Good Enough - 00
0000-00
When Does a Hydrogen-Ready Gas Turbine Pay Off? - 00
0000-00
Electricity Price Volatility Is Rewriting Hydrogen Cost Models - 00
0000-00
PSA Recovery Rate Drops for Reasons Operators Miss
Dr. Hideo Torque
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.